
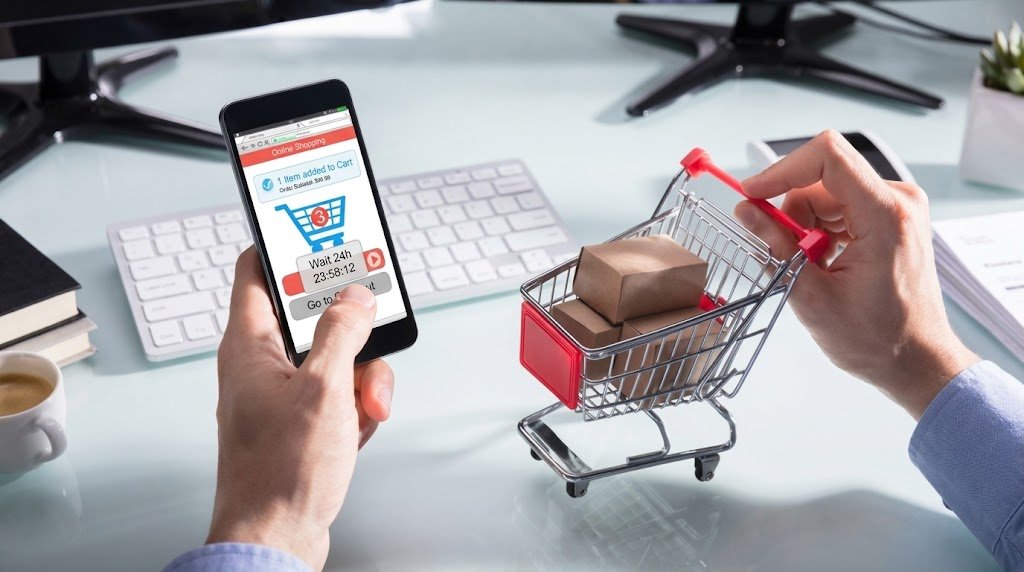
You’re scrolling, you see something, and before you’ve really thought about it, it’s in your cart and the order is placed. The 24-hour rule for spending is a simple behavioral trick designed to interrupt that exact moment — not by banning purchases, but by forcing a delay long enough for the impulse to fade before the money leaves your account.
Here’s how the rule actually works, why the delay itself is what makes it effective, and how to apply it in a way that actually sticks.
What Is the 24-Hour Rule for Spending?
The 24-hour rule for spending is a simple guideline: before making a non-essential purchase above a certain amount, you wait 24 hours before buying it. If you still want the item after the waiting period, you buy it. If the urge has faded, you don’t.
The rule doesn’t restrict what you can buy or how much you can spend overall — it simply inserts a mandatory pause between the impulse and the transaction, giving your slower, more deliberate thinking a chance to catch up with the faster, more emotional reaction that drives most impulse purchases.
The Psychology Behind Why the 24-Hour Rule Works
Impulse Purchases Are Driven by a Short-Lived Emotional Spike
Behavioral research on impulse buying consistently shows that the urge to purchase something on impulse is often tied to a temporary emotional state — excitement, stress, boredom, or the dopamine hit of seeing something new — rather than a genuine, stable need for the item. That emotional spike is often short-lived, which is exactly why a delay, even a brief one, can be enough to let it pass.
Delaying a Decision Shifts You Into Slower, More Deliberate Thinking
Psychologists distinguish between fast, automatic decision-making and slower, more analytical thinking. Impulse purchases happen almost entirely in the fast system — an emotional reaction converted immediately into an action. Introducing a mandatory delay forces the decision into the slower system, where questions like “do I actually need this” and “does this fit my budget” have a chance to surface.
The Rule Removes the Permanence of “Right Now”
Retailers and apps are specifically designed to create urgency — limited-time offers, low-stock warnings, one-click checkout — all engineered to compress the decision window as much as possible. The 24-hour rule for spending directly counteracts this by reintroducing the delay that urgency-based marketing is specifically built to eliminate.
How to Actually Apply the 24-Hour Rule
Set a Specific Dollar Threshold
Applying the rule to every single purchase, including small everyday items, quickly becomes impractical and is likely to be abandoned. Most people apply the 24-hour rule for spending only above a specific threshold — commonly somewhere between $50 and $150, depending on their overall budget — reserving the delay for purchases significant enough to matter.
Write It Down Instead of Just Thinking About It
Rather than relying on memory or willpower alone, keeping a simple running list — item, price, and the date you first considered it — creates a concrete record you can revisit after the 24 hours has passed, rather than trusting yourself to remember the impulse accurately.
Remove the Item From Your Cart, Don’t Just Leave It There
Actively removing the item from your cart or closing the tab, rather than leaving it sitting there “for later,” breaks the visual reminder that can keep reactivating the original impulse throughout the waiting period.
Extend the Rule for Larger Purchases
For genuinely large purchases — furniture, electronics, anything in the hundreds or thousands of dollars — many people extend the waiting period well beyond 24 hours, sometimes to a full week, since the stakes and potential regret scale with the purchase size.
Why the 24-Hour Rule for Spending Works Better Than Willpower Alone
It Doesn’t Rely on Saying No in the Moment
Most spending advice asks you to resist temptation at the exact moment it’s strongest — arguably the hardest possible time to make a rational decision. The 24-hour rule sidesteps this entirely by not requiring a decision at all in that moment; it simply requires waiting, which is a much lower bar than immediate self-denial.
It Still Allows the Purchase
Unlike a strict no-spend rule, the 24-hour rule for spending doesn’t forbid the purchase — it just delays it. This matters psychologically, since restrictive rules that feel punishing are far more likely to be abandoned or lead to a rebound binge, while a rule that simply asks for patience feels more sustainable long-term.
It Creates a Natural Audit Trail
Because the rule requires tracking what you’re considering buying, it naturally surfaces patterns over time — certain categories, certain triggers, certain times of day when impulse urges spike most. This kind of pattern recognition can be more useful for long-term spending habits than the rule itself.
Where This Connects to Bigger Spending Patterns
Impulse Spending and Silent Money Leaks Often Overlap
The same impulsivity that drives a one-time purchase can also be behind recurring charges that quietly build up over time. If you notice the 24-hour rule catching frequent small impulse buys, it’s worth also checking for silent money leaks — the forgotten subscriptions and small recurring charges that follow a similar impulsive pattern but continue draining money every month rather than just once.
Understanding Your Spending Type Helps the Rule Stick
The 24-hour rule tends to help some spending personalities more than others. Someone who leans heavily toward impulsive, emotion-driven purchases is likely to benefit the most from the delay, while someone whose spending challenges come from avoidance rather than impulsivity may need a different approach entirely. Taking a money personality test can help clarify which pattern actually applies to you, so you’re not applying a rule designed for one type of spender to a completely different underlying problem.
A Rising Income Can Make the Rule More Important, Not Less
As income grows, the dollar threshold for what feels like a “small” impulse purchase tends to grow along with it, often without a deliberate decision to raise it. This is part of how lifestyle inflation quietly takes hold — the 24-hour rule can act as a check against that drift, since the pause forces a conscious decision rather than letting the spending threshold rise passively alongside a bigger paycheck.
When the 24-Hour Rule Isn’t Enough
For some people, especially those dealing with compulsive spending patterns tied to significant financial or emotional distress, a simple delay tactic may not be sufficient on its own. If impulse spending is causing serious financial strain or feels genuinely outside your control despite consistent effort to manage it, it may be worth talking to a financial counselor or a mental health professional, since compulsive spending can sometimes be connected to underlying stress, anxiety, or other patterns that a delay tactic alone won’t fully address.
Final Thoughts
The 24-hour rule for spending works because it targets the actual mechanism behind impulse purchases — a short-lived emotional spike — rather than relying on willpower to override that spike in the moment it’s strongest. By simply inserting a mandatory pause, the rule gives your slower, more deliberate thinking a real chance to weigh in before the money is spent.
It’s not a complete budgeting system on its own, but as a simple, low-effort habit, it can meaningfully reduce impulse spending without requiring the kind of constant vigilance that more restrictive approaches demand.

