Most people think their financial habits come down to willpower or income. But research in behavioral finance suggests something else is often driving the wheel: a deeper money personality that shows up the same way again and again, regardless of how much you make. This money personality test is designed to help you spot that pattern in yourself, in a few minutes, without needing a spreadsheet or a financial advisor.
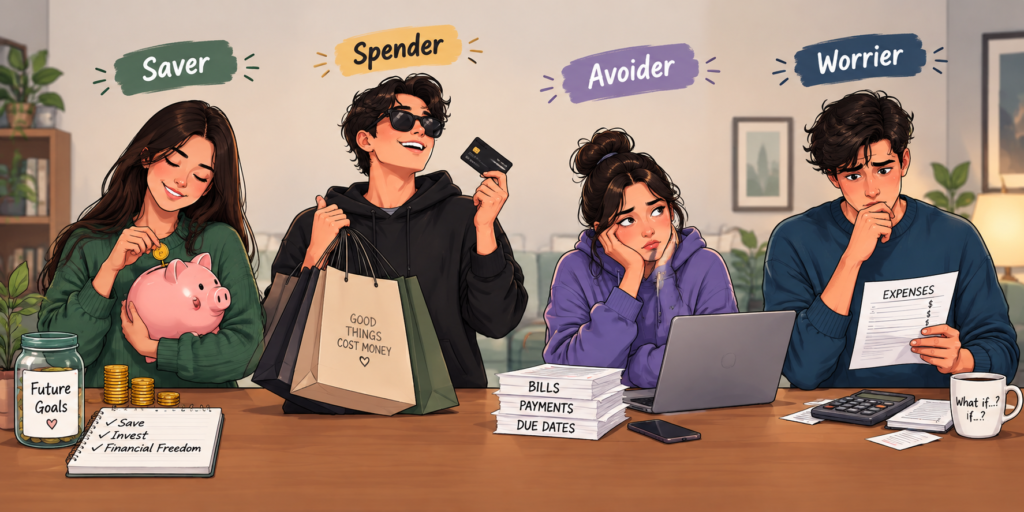
This isn’t a licensed psychological assessment, but a widely used framework in financial coaching and behavioral finance circles identifies four common money personality types: the Saver, the Spender, the Avoider, and the Worrier. Most people are a blend, with one type dominating. Answer honestly, and see which one sounds most like you.
Take the Money Personality Test
Read each statement and note how often it’s true for you: Rarely, Sometimes, or Often.
- I feel anxious or guilty after spending money, even on things I can afford.
- I avoid checking my bank balance because I don’t want to know.
- I get a genuine emotional lift from buying something new.
- I have a savings goal, but I rarely feel like I’ve saved “enough.”
- I know almost exactly how much money I have at any given time.
- I put off financial decisions — opening statements, filing taxes, checking credit — for as long as possible.
- I’d rather buy an experience or gift now than save it for later.
- I lie awake occasionally thinking about a bill, a balance, or a “what if” scenario.
However you answer, this money personality test works best when you’re honest rather than aspirational — answer as you actually behave, not as you wish you did. Keep track of which statements you answered “Often” to. Now let’s break down what each pattern typically means, and what this money personality test reveals about your financial habits.
The Saver
If you related most to statement 5, and generally feel calm rather than anxious about money, you likely lean Saver.
Savers find genuine satisfaction in watching an account balance grow. Saving isn’t a chore for this type — it’s closer to a source of security and even identity. The upside is obvious: Savers tend to build financial cushions faster than other types and rarely carry high-interest debt.
The blind spot: Savers can sometimes hold onto money so tightly that they miss opportunities — delaying reasonable investments, avoiding calculated risks, or under-spending on things that would genuinely improve their quality of life. Financial security can quietly tip into financial rigidity.
If this is you: Set a specific “permission to spend” amount each month for something enjoyable, guilt-free. It won’t undo your saving habits — it will just keep them from curdling into deprivation. This pattern is one of the clearest signals this money personality test is designed to catch.
The Spender
If you related most to statement 3 or 7, and buying things gives you a real emotional charge, you likely lean Spender.
Spenders are often generous, present-focused, and comfortable enjoying money rather than treating it purely as a tool for the future. That’s not inherently a flaw — but Spenders are also the type most likely to experience silent money leaks, the small recurring subscriptions and forgotten charges that quietly drain a paycheck, since tracking every dollar often feels less appealing than simply spending it.
The blind spot: Without structure, Spenders can end up financing a lifestyle they can’t fully support — sometimes leaning on credit cards to bridge the gap between income and spending.
If this is you: Automate savings and bill payments the moment income arrives, before you see the money in your checking account. Removing the decision point is far more effective than relying on willpower in the moment. Recognizing this tendency is often the single biggest takeaway Spenders get from a money personality test like this one.
The Avoider
If you related most to statement 2 or 6, and financial tasks feel like something to postpone rather than confront, you likely lean Avoider.
Avoiders aren’t necessarily bad with money — they’re often simply overwhelmed by it, or associate financial tasks with stress they’d rather not sit with. The habit of not looking is a coping mechanism, not a character flaw, but it has real costs: unopened bills, missed due dates, and a general lack of visibility into where money is actually going.
The blind spot: Avoidance means problems compound quietly. A missed credit card payment that could have been caught and fixed within days can spiral into real credit damage simply because it went unnoticed for weeks.
If this is you: Start with a single low-stakes ritual — checking your balance once a week, same day, same time, no judgment attached. The goal isn’t a perfect budget overnight; it’s simply breaking the avoidance pattern. Avoiders are usually the group most surprised by their own results on a money personality test, simply because they’ve never stopped to look this closely before.
The Worrier
If you related most to statement 1, 4, or 8, and money triggers anxiety even when your situation is objectively stable, you likely lean Worrier.
Worriers often manage money responsibly on paper — they save, they budget, they pay bills on time — but rarely feel a sense of security from doing so. The number in the account never quite feels like “enough,” and financial decisions can come with disproportionate stress.
The blind spot: Chronic financial anxiety can lead to two opposite problems: either overly conservative decisions that miss legitimate opportunities (like reasonable investing), or occasional stress-driven decisions made just to “make the anxious feeling stop.”
If this is you: A concrete, written financial plan — even a simple one — tends to help more than additional saving does, because the anxiety is often about uncertainty, not actual numbers. Knowing exactly what you’re saving for, and having a clear target, can quiet the background noise more than a bigger balance alone. If this section felt uncomfortably familiar, that’s exactly the kind of insight a money personality test is meant to surface.
Why This Money Personality Test Actually Matters
Generic budgeting advice assumes everyone struggles with money the same way — usually framed as “just spend less.” But a Saver and an Avoider don’t have the same problem, so they don’t need the same fix. Someone who already tracks every dollar (a Saver leaning toward rigidity) needs different advice than someone who hasn’t opened a bank statement in three months (an Avoider). This is exactly why a money personality test is more useful than a one-size-fits-all budgeting tip.
Financial behavior researchers, including those cited by the Consumer Financial Protection Bureau’s Your Money, Your Goals program, have found that money habits are shaped as much by psychology, upbringing, and emotional association as by income or financial literacy alone — which is part of why purely numbers-based budgeting advice doesn’t work equally well for everyone.
When Your Money Personality Test Result Collides With Debt
Certain personality types are more prone to specific financial risks. Spenders and Avoiders, in particular, are more likely to end up carrying debt they didn’t fully plan for — whether through overspending or simply losing track of bills.
If that describes your pattern, it’s worth understanding the real stakes before the situation escalates. Knowing what actually happens if you default on a personal loan — from credit score damage to potential collections — can be a useful, sobering reference point, especially for an Avoider type who might otherwise be tempted to put off dealing with a growing balance.
Most People Are a Mix — And That’s Normal
Few people are a pure Saver or pure Spender. It’s common to be, say, a Saver with income but a Worrier under financial stress, or a Spender who becomes an Avoider the moment a bill feels too large to face. The goal of this money personality test isn’t to put you in a permanent box — it’s to notice the emotional pattern that tends to drive your financial decisions, so you can build habits that work with your psychology instead of fighting it.
Final Thoughts
Your result on this money personality test isn’t a fixed trait — it’s a pattern, and patterns can shift with awareness and small structural changes. Whether you lean Saver, Spender, Avoider, or Worrier, the goal isn’t to force yourself into a completely different mindset. It’s to recognize your blind spot and build one or two habits that specifically counter it, rather than adopting generic advice that was never designed with your particular relationship to money in mind.