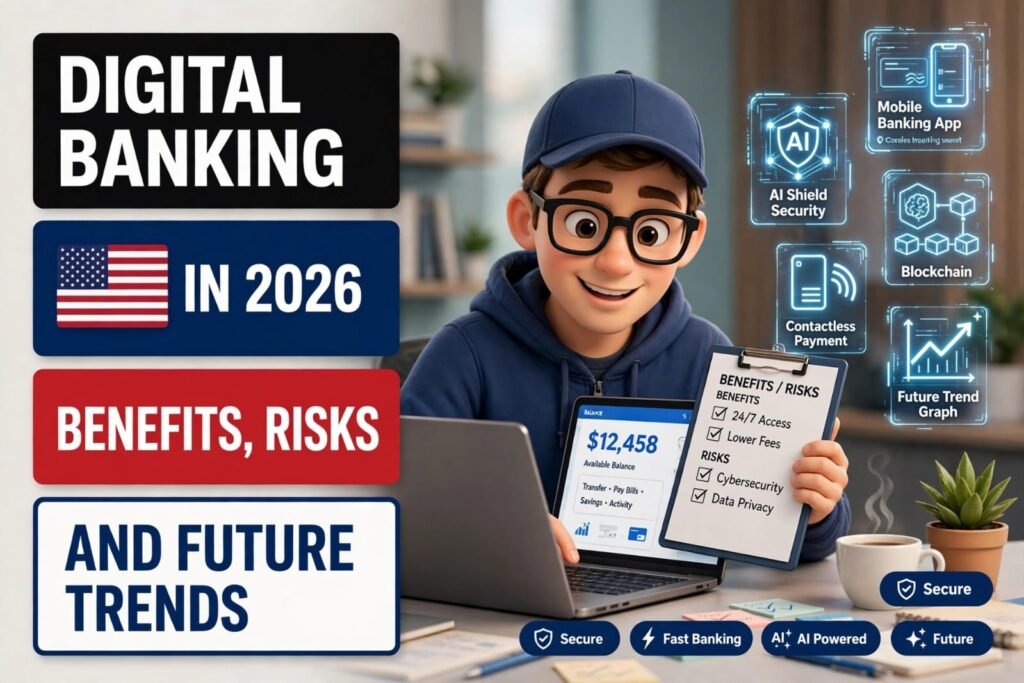
Digital Banking in 2026: Benefits, Risks and Future Trends
Digital banking is changing the way people manage their money in 2026. Digital banking makes it easier to check balances, transfer money, pay bills, manage cards, and access financial services through mobile apps and websites. As technology continues to develop, banks are introducing new digital tools, faster payments, artificial intelligence, and stronger security features.
What Is Digital Banking?
Digital banking allows customers to access banking services through websites, mobile applications, and other digital platforms instead of visiting a physical branch.
Customers can check balances, transfer money, pay bills, manage cards, apply for certain financial products, and receive account notifications through digital channels.
The growth of digital banking has also encouraged traditional banks to improve their online services while creating opportunities for digital-first financial companies.
Benefits of Digital Banking in 2026
One of the biggest benefits of digital banking is convenience. Customers can access many banking services at almost any time without travelling to a branch.
Digital platforms can also make everyday transactions faster. Transfers, bill payments, and account management can often be completed within minutes.
Another benefit is improved access to financial information. Mobile applications can provide instant notifications about transactions, balances, and spending activity.
Digital services may also help financial institutions reduce some operational costs and offer more automated customer support.
Artificial Intelligence in Digital Banking
Artificial intelligence is becoming an important part of modern financial services. Banks are using AI for areas such as fraud detection, customer service, risk management, and compliance.
AI can analyze large amounts of financial data and identify unusual patterns that may require further investigation. Financial institutions are also exploring AI assistants that can help customers find information and complete routine tasks.
However, AI creates new cybersecurity and governance challenges. The International Monetary Fund has highlighted how AI can strengthen cyber defenses while also increasing the speed and scale of cyber threats.
Digital Banking and Faster Payments
Digital banking is closely connected with the growth of faster electronic payments.
Customers increasingly expect payments to be convenient and available through mobile devices. This trend is encouraging financial institutions to improve payment infrastructure and develop easier ways to send and receive money.
Digital payment systems can also support people who previously had limited access to traditional financial services.
However, faster payments can create additional challenges because fraudulent transactions may happen quickly. Financial institutions therefore need effective monitoring and authentication systems.
Major Risks of Digital Banking
Digital banking offers convenience, but it also creates risks that customers should understand.
Cybersecurity is one of the biggest concerns. Criminals may attempt to steal login information, take over accounts, conduct fraudulent transactions, or use social engineering techniques.
Digital fraud is also becoming more sophisticated. An IMF working paper published in March 2026 found that cyber-enabled fraud had nearly tripled in its examined data, while noting that fraud is still underestimated because of reporting and data limitations.
Privacy is another concern because digital financial services process large amounts of sensitive customer information.
Customers should use strong passwords, enable available security features, avoid suspicious links, and regularly check account activity.
How Banks Are Improving Digital Security
Banks are investing in stronger authentication, fraud monitoring, transaction alerts, and cybersecurity systems.
Some financial institutions are also using AI to identify suspicious behavior and improve fraud detection.
For example, financial authorities and banks in Singapore have been working on stronger authentication, transaction protections, and AI-assisted scam detection.
Security is becoming increasingly important because digital banking connects financial institutions with shared software, cloud services, payment networks, and other technology infrastructure.
The IMF has warned that weaknesses in widely used digital infrastructure can potentially spread across multiple financial institutions, making resilience and recovery planning increasingly important.
The Future of Digital Banking
The future of digital banking is likely to involve greater automation, more personalized financial services, and stronger integration between banking and other digital platforms.
Artificial intelligence could help banks provide more personalized financial insights, detect unusual activity faster, and automate routine customer-service tasks.
Open banking and connected financial services may also give customers more ways to view and manage financial information across different platforms, depending on local regulations and infrastructure.
Digital finance is also expanding into areas such as stablecoins, tokenization, and central bank digital currencies. The IMF’s 2026 annual report identifies these areas as important developments in the broader future of digital finance.
Digital Banking and Financial Inclusion
Another important potential benefit is financial inclusion.
Digital services can make basic financial products more accessible to people who live far from traditional bank branches.
Mobile devices can provide access to payments, savings, credit, and other services where digital infrastructure is available.
The Bank for International Settlements notes that digital innovation can improve access to payments, credit, savings, and insurance, while also creating risks such as fraud and overindebtedness.
How to Use Digital Banking Safely
Customers can take several simple steps to reduce common digital banking risks.
Use unique and strong passwords for financial accounts and enable multifactor authentication whenever it is available.
Never share one-time passwords, PINs, or banking credentials with another person.
Avoid logging into financial accounts through suspicious links received by email or text messages.
Keep banking applications and phone operating systems updated.
Regularly review account activity and contact the bank quickly if an unfamiliar transaction appears.
These basic habits can make digital banking safer without making everyday financial management unnecessarily complicated.
Digital Banking Trends to Watch
Several trends are likely to remain important as digital financial services develop.
AI-powered fraud detection is expected to become more advanced as banks use technology to identify unusual transactions and cyber threats.
Mobile-first banking will continue to influence how customers interact with financial institutions.
Digital payments are likely to become increasingly integrated into everyday shopping and online services.
At the same time, banks and regulators will need to focus on privacy, cybersecurity, operational resilience, and responsible use of AI.
Digital banking in 2026 offers faster access, convenient financial management, digital payments, and increasingly intelligent financial services. At the same time, customers need to understand cybersecurity, privacy, fraud, and technology-related risks.
The future of digital banking will likely depend on how effectively financial institutions combine innovation with security and responsible technology management.
For customers, the most important step is to use digital services carefully, stay aware of new security threats, and make use of the protection features provided by their financial institution.
Want to learn more about money, budgeting, and personal finance? Visit our website for the latest updates, useful tips, and interesting financial stories.https://corefoxes.com/best-ai-budgeting-tools-to-manage-your-money-in-2026/