
When you use a credit card, a transaction does not always move directly from purchase to final charge. Sometimes a merchant cancels, voids, or reverses a transaction before it fully posts to your account.
This can happen for several reasons. A merchant may accidentally process a transaction twice, cancel an order, experience a payment-processing problem, or realize that the final amount needs to be changed.
When this happens, you may notice a pending transaction disappear, your available credit increase, or a temporary charge be removed from your account.
Understanding what happens when a credit card merchant cancels or voids a transaction can help you avoid confusion when checking your balance and available credit.
What Does It Mean When a Credit Card Transaction Is Voided?
A voided credit card transaction is generally a transaction that the merchant cancels before it becomes a completed, posted charge.
For example, suppose you purchase an item for $100 using your credit card. The merchant sends the transaction for authorization, and your available credit decreases by $100.
Later, the merchant realizes that the order cannot be fulfilled and voids the transaction.
Instead of becoming a final $100 charge, the transaction may disappear or be removed from your pending transactions.
The exact process can vary depending on the merchant, card issuer, payment network, and timing.
What Is the Difference Between a Voided and Refunded Transaction?
Voided transactions and refunds are related, but they are not exactly the same.
A void generally happens before a transaction has fully settled or posted. The merchant cancels the transaction before it becomes a completed charge.
A refund generally happens after the original transaction has already been completed and posted.
For example, imagine you purchase a $200 product.
If the merchant cancels the transaction before it settles, the transaction may be voided.
If the merchant completes the $200 charge and you later return the product, the merchant may issue a $200 refund.
This distinction matters because the timing of when your available credit and account balance change can be different.
What Happens to a Pending Credit Card Transaction?
If a merchant voids a transaction while it is still pending, the pending transaction may eventually disappear from your account.
For example, suppose you make a $150 purchase.
Your credit card account may initially show:
- Credit limit: $5,000
- Available credit before purchase: $3,000
- Pending transaction: $150
- Available credit after authorization: approximately $2,850
If the merchant voids the transaction, the $150 authorization may be released.
Your available credit could then return to approximately $3,000.
This is one reason a pending transaction should not always be treated as a permanent charge.
A pending transaction can represent an authorization rather than a finalized purchase. Our recent guide on credit card authorization holds explains how temporary authorizations can reduce your available credit before a transaction becomes final.
Why Would a Merchant Void a Credit Card Transaction?
There are many reasons a merchant might cancel or void a transaction.
The Customer Cancels the Order
A customer may cancel an order shortly after placing it.
If the transaction has not yet settled, the merchant may be able to void the payment instead of issuing a traditional refund.
The Merchant Makes a Mistake
A cashier or employee may accidentally enter the wrong amount.
For example, a $50 purchase could accidentally be processed as $500.
The merchant may void the incorrect transaction and process the correct amount.
Duplicate Transaction
Sometimes a payment may accidentally be submitted more than once.
If two identical transactions are created, the merchant may void one of them before it settles.
Payment Processing Problems
Technical problems can also cause a merchant to cancel or restart a transaction.
The merchant may need to void the original authorization before attempting the payment again.
Product or Service Is Unavailable
An online store may accept an order and authorize the customer’s card before discovering that the item is unavailable.
If the order cannot be fulfilled, the merchant may cancel the transaction.
Does a Voided Transaction Affect Your Credit Card Balance?
Usually, a transaction that is successfully voided before posting does not become part of your final credit card balance.
However, the timing can make your account temporarily confusing.
You might see the transaction listed as pending before it disappears.
You may also notice that your available credit changes before the transaction completely disappears from your account.
For example, a $300 authorization could temporarily reduce your available credit. Once the merchant’s authorization is released, that amount may become available again.
The important point is that a temporary authorization is not necessarily the same thing as a completed charge.
How Long Does It Take for a Voided Transaction to Disappear?
There is no single timeframe that applies to every credit card transaction.
The timing can depend on the merchant, card issuer, payment network, transaction type, and whether the transaction had already moved into another stage of processing.
Some voided transactions may disappear relatively quickly.
Others may remain visible as pending for several days before the authorization is released.
If you see a transaction marked as pending, do not automatically assume that you will permanently owe that amount.
Instead, monitor the account to see whether the transaction posts, disappears, or is replaced by another amount.
What Happens to Your Available Credit After a Transaction Is Voided?
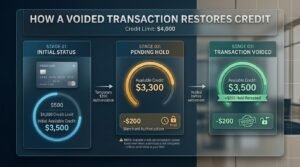
When a transaction is voided, the amount that was temporarily reserved may become available again.
Suppose you have a $4,000 credit limit and $3,500 of available credit.
A merchant places a $200 authorization on your card.
Your available credit may temporarily fall to $3,300.
If the merchant voids the transaction before it settles, the $200 authorization may be released.
Your available credit could then return to $3,500.
This can be especially important if you are close to your credit limit.
A temporary authorization may make your available credit look lower than expected even though you have not actually completed the purchase.
Can a Merchant Void a Transaction After It Posts?
Generally, once a transaction has fully settled, the merchant may need to process a refund rather than simply void the original transaction.
This is an important difference.
A void prevents an authorized transaction from becoming a completed charge.
A refund sends money back after a completed transaction has already been processed.
For example:
Before settlement: Merchant cancels the transaction → transaction may be voided.
After settlement: Merchant cancels the purchase → merchant may issue a refund.
The exact process depends on the merchant and payment system.
What If the Transaction Does Not Disappear?
Sometimes a merchant tells you that a transaction has been cancelled, but you continue seeing it on your credit card account.
Do not immediately assume that the merchant has charged you incorrectly.
First, check whether the transaction is:
- Pending
- Posted
- Reversed
- Refunded
- Still under authorization
If it remains pending, it may simply take additional time to disappear.
If it posts as a completed transaction even though the merchant confirmed that the purchase was cancelled, contact the merchant first and ask for clarification.
Keep any cancellation confirmation, receipt, email, or order information.
What If You Are Charged After the Merchant Cancels the Transaction?
If a merchant confirms that a transaction was cancelled but the charge eventually posts, contact the merchant and your card issuer.
Ask the merchant to confirm whether the transaction was actually voided or whether a refund was issued.
If the merchant agrees that the charge should not have been completed but does not correct the problem, you may have the option to dispute the charge.
Our guide on how to dispute a credit card charge explains the billing-error process and the information you may need when challenging an incorrect transaction.
Keep records of your communication with the merchant because documentation can make it easier to explain what happened.
Can a Voided Transaction Affect Your Credit Score?
A normal merchant void generally does not directly damage your credit score.
The transaction itself is not a new credit account or a missed payment.
However, credit card activity can affect your credit profile indirectly depending on your balances and utilization.
For example, if a temporary authorization causes confusion and you make another purchase that pushes your actual balance higher, your reported credit utilization could eventually change.
The key distinction is that a cancelled transaction itself is not normally treated like a late payment or other negative credit event.
What Should You Do When a Merchant Voids a Transaction?
Usually, you do not need to take any special action.
Monitor your credit card account and confirm that the transaction eventually disappears or is handled correctly.
You should also check your available credit because the amount previously reserved by the authorization may become available again.
If you receive confirmation from the merchant that the transaction was cancelled, keep that confirmation until the transaction is completely resolved.
If you use a credit card for purchases that include additional protections, benefits may also matter. Our article on credit card perks and purchase protection explains some of the benefits that certain cards may provide.
Final Thoughts
When a credit card merchant cancels or voids a transaction, the transaction may never become a finalized charge.
If the transaction was still pending, the authorization may be released and your available credit may increase again. If the transaction had already posted, the merchant may need to issue a refund instead.
The most important thing is to understand the difference between an authorization, a pending transaction, a posted charge, a void, and a refund.
If a merchant tells you that a transaction has been cancelled, monitor your credit card account until the transaction is properly removed or corrected. If a charge posts despite the cancellation and the merchant does not resolve the issue, contacting your card issuer may be the next step.
Understanding how these transactions work can make it much easier to manage your credit card balance and avoid unnecessary confusion.

