
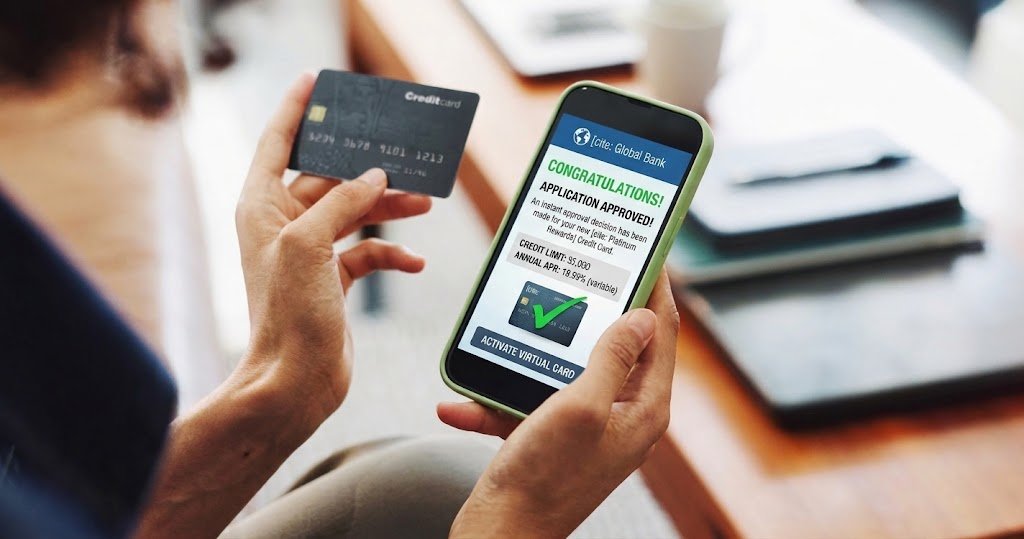
Instant approval credit cards promise something that sounds almost too easy: apply online, get a decision in under a minute, and start using a digital card number before the physical one even arrives in the mail. For a financial product that used to take days or weeks to get approved, that speed naturally raises a question — what’s the catch?
The short answer is that instant approval credit cards aren’t a scam, but they’re also not quite what the marketing implies. Understanding what’s actually happening behind that fast decision matters more than the speed itself.
What “Instant Approval” Actually Means
When a card is marketed with instant approval, it usually means the issuer runs an automated underwriting check — a quick pull of your credit report and a few other data points — and returns a preliminary decision in real time, rather than routing the application to a human reviewer.
That said, “instant” doesn’t always mean final. According to guidance from the Consumer Financial Protection Bureau, some applications that appear instantly approved are still subject to further review, and the final terms — credit limit, APR — may not be confirmed until later. A small number of “instant” decisions turn out to be conditional rather than truly final.
Why Instant Approval Credit Cards Can Be a Good Deal
For qualified applicants, instant approval credit cards genuinely deliver real value. The speed itself isn’t the catch — it’s simply automation replacing manual review for straightforward cases.
Many issuers now provide a virtual card number immediately upon approval, usable for online purchases before the physical card arrives — useful for someone who needs to make a purchase right away. The application process typically triggers what’s called a hard inquiry, and according to FICO, a single hard inquiry usually has a small, temporary effect on a score — often just a few points. That’s the same inquiry that would happen with a slower, traditionally reviewed application, so instant approval doesn’t add extra risk on that front.
Where the “Too Good to Be True” Feeling Comes From
The skepticism around instant approval credit cards usually isn’t unfounded — it just tends to point at the wrong part of the process.
Approval isn’t the same as good terms. An instant approval credit card can come with a high APR, a low starting limit, or an annual fee that isn’t obvious in the ad. The speed of the decision has nothing to do with how favorable the card actually is.
Rejections can still happen instantly. Automated systems decline applications just as quickly as they approve them, and a rejected application still generates a hard inquiry on your credit report — a cost with no card to show for it.
Pre-qualification offers aren’t the same as approval. Many “you’re pre-qualified” emails and ads use a soft inquiry that doesn’t affect your score, but people sometimes assume pre-qualification guarantees the instant approval that follows. It doesn’t — the actual application still runs a full check.
Some cards target thin or no credit files aggressively. A few instant approval credit cards are marketed heavily at people with limited credit history, sometimes carrying higher fees than a comparable secured card would, functioning less like an entry point and more like a secured credit card without the deposit protection or the lower cost.
How to Evaluate an Instant Approval Credit Card Before Applying
A fast decision doesn’t mean the decision to apply should be fast too.
- Read the full terms before applying, not just the headline offer — APR, annual fee, and rewards structure matter more than approval speed.
- Check whether it’s a soft or hard inquiry at the pre-qualification stage, and understand that the real application will likely be a hard inquiry regardless.
- Compare it to a secured card if your credit history is thin or damaged — sometimes the “faster” option isn’t actually the cheaper or more useful one.
- Confirm it reports to all three credit bureaus, since an instant approval credit card that doesn’t report does little to build a credit history.
- Avoid applying to several instant approval credit cards in a short window, since each hard inquiry adds up and multiple rejections can compound the impact.
Treating the application the same way you’d treat any other financial decision — checking terms, not just chasing speed — fits the same logic behind automating your finances: build the system deliberately once, rather than reacting to whatever looks fastest in the moment.
Who Instant Approval Credit Cards Actually Suit
Instant approval credit cards tend to work best for people who already have decent credit and just want convenience — a known quantity, applied for and confirmed quickly. They’re a less reliable fit for someone rebuilding credit after a rough patch, where the terms behind the speed matter far more than the wait time ever would.
For some applicants, the appeal of instant approval credit cards is less about convenience and more about avoiding a slower process that feels uncomfortable to sit with — a pattern that can trace back to underlying money scripts around urgency or avoidance when it comes to money decisions.
Final Thoughts
Instant approval credit cards aren’t too good to be true — the speed is simply automation doing what a human reviewer used to do manually. The real question was never how fast the decision arrives. It’s what’s actually inside the card once the decision is made.
Read the terms, check the reporting, and treat the application with the same care as any slower one. The instant part is just the process. The value still depends on everything that comes after.

