
A personal loan cosigner is someone who agrees to take responsibility for a loan alongside the primary borrower. A cosigner can sometimes help a borrower qualify for financing when their credit history, income, or other financial factors are not strong enough to meet a lender’s requirements on their own.
However, becoming a cosigner is a serious financial commitment. The cosigner may be responsible for making payments if the primary borrower fails to do so, and the loan can affect the cosigner’s credit profile.
Understanding how a personal loan cosigner works can help both borrowers and potential cosigners understand the responsibilities and risks before signing a loan agreement.
What Is a Personal Loan Cosigner?
A cosigner is a person who agrees to share legal responsibility for repaying a loan with the primary borrower.
The primary borrower receives the loan funds and is generally responsible for making the scheduled payments. However, the cosigner provides an additional repayment commitment to the lender.
For example, suppose someone wants to borrow $15,000 but does not meet a lender’s credit or income requirements. A family member with stronger credit and sufficient income may agree to cosign the loan.
If the lender approves the application, both individuals may be legally responsible for the debt according to the loan agreement.
The exact responsibilities can vary by lender and contract, so the cosigner should read the agreement carefully before signing.
How Does a Personal Loan Cosigner Work?
The process usually begins when the borrower applies for a personal loan.
If the lender determines that the borrower may need additional support, the borrower may apply with a cosigner. The lender can then evaluate information about both people.
This may include:
- Credit history
- Credit score
- Income
- Existing debt
- Debt-to-income ratio
- Employment or income stability
- Other information required by the lender
If the lender approves the application, the borrower receives the loan according to the agreed terms.
The borrower generally makes the monthly payments. However, if the borrower does not make payments as required, the cosigner may become responsible for satisfying the debt.
Why Might Someone Need a Cosigner?
A borrower may consider a cosigner for several reasons.
One common reason is limited credit history. Someone who has not borrowed much money in the past may have difficulty qualifying for certain loans.
Another reason may be a lower credit score. A borrower with past credit problems may find that some lenders offer less favorable terms or may not approve the application without additional support.
Income can also matter. If the borrower’s income is insufficient for the lender’s requirements, a cosigner with qualifying income may strengthen the application.
However, a cosigner does not guarantee approval. The lender still makes the final decision based on its own eligibility requirements.
Can a Cosigner Help You Get a Better Loan Rate?
A cosigner with a stronger credit profile or financial position may potentially help a borrower qualify for different loan terms.
However, there is no guarantee that adding a cosigner will result in a lower interest rate.
The lender determines the rate based on its underwriting criteria, which can include credit history, income, debt, loan amount, repayment term, and other factors.
Borrowers should compare the full cost of the loan rather than assuming that a cosigned loan is automatically cheaper.
For example, a lower monthly payment can sometimes result from a longer repayment period. That can increase the total interest paid over the life of the loan.
Understanding the complete cost is important before accepting an offer. CoreFoxes explains this in How to Calculate the True Cost of a Personal Loan Before You Sign, including interest, fees, repayment terms, and the amount of cash actually received.
What Is the Difference Between a Cosigner and a Co-Borrower?
The terms cosigner and co-borrower can sometimes be confused, but they may have different meanings depending on the lender and loan agreement.
A co-borrower generally applies for the loan jointly and may receive a direct benefit from the borrowed funds. Both borrowers may be considered primary parties to the loan.
A cosigner, on the other hand, generally provides additional repayment support for the primary borrower.
The exact legal responsibilities can vary, so borrowers and cosigners should review the specific agreement rather than relying only on the terminology used by a lender.
What Responsibilities Does a Cosigner Have?
A cosigner should understand that signing the loan is a significant financial commitment.
Depending on the loan agreement, the cosigner may be responsible for the debt if the primary borrower fails to make payments.
Before agreeing to cosign, consider:
- The total loan amount
- Interest rate and APR
- Monthly payment
- Repayment term
- Potential fees
- Late payment provisions
- Default provisions
- The borrower’s ability to repay
A cosigner should not assume that their responsibility ends simply because another person is making the regular payments.
Can a Personal Loan Affect the Cosigner’s Credit?
A cosigned personal loan can affect the cosigner’s credit profile.
The loan may appear on the cosigner’s credit reports, depending on the lender and reporting practices. Payment history can therefore become relevant to the cosigner’s credit history.
If payments are made on time, the account may be reported as current. However, missed or late payments can create negative information.
The cosigner’s existing debts and the new loan may also be considered by lenders when evaluating future applications.
For example, if the cosigner later applies for a mortgage or another personal loan, the cosigned debt could be relevant to the lender’s assessment of their financial obligations.
What Happens If the Borrower Misses a Payment?
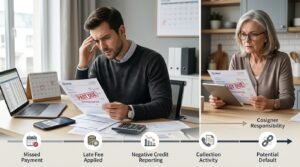
If the primary borrower misses a payment, the consequences depend on the loan agreement and how late the payment becomes.
Potential consequences can include:
- Late fees
- Negative credit reporting
- Increased financial costs
- Collection activity
- Default
- Responsibility for payment by the cosigner
The cosigner should not wait until a missed payment becomes a major problem.
If the borrower experiences financial difficulty, both parties should review the loan terms and communicate with the lender as soon as possible.
What Happens If the Borrower Defaults?
A default occurs when the borrower fails to meet the loan’s repayment requirements according to the lender’s terms.
If the borrower defaults, the lender may seek repayment from the cosigner according to the agreement.
This is one of the most important reasons a cosigner should treat the loan as if they could eventually become responsible for the payments.
Before signing, a potential cosigner should ask themselves whether they could realistically afford the payment if the primary borrower could no longer make it.
If the answer is no, cosigning could create significant financial pressure.
How Does a Cosigned Loan Affect Debt-to-Income Ratio?
Debt-to-income ratio, or DTI, compares monthly debt obligations with gross monthly income. A cosigned loan may be considered when a lender evaluates the cosigner’s existing obligations, depending on the lender’s policies and circumstances. You can learn more about this calculation in Debt-to-Income Ratio Explained: What Lenders Look at Before Approving Your Loan.
A cosigned loan may be considered when a lender evaluates the cosigner’s existing obligations, depending on the lender’s policies and circumstances.
This could matter if the cosigner plans to apply for another loan in the future.
For example, someone may agree to cosign a $20,000 personal loan and later apply for a mortgage. The lender may ask about the cosigned obligation when assessing the person’s overall financial situation.
DTI is only one factor lenders may consider, but it is important to understand how additional debt can affect future borrowing.
What Should You Ask Before Cosigning?
Before signing a personal loan as a cosigner, ask the borrower and lender important questions.
What Is the Total Loan Cost?
Review the interest rate, APR, fees, monthly payment, and total repayment amount.
How Long Is the Loan Term?
A longer term may reduce the monthly payment but can increase total interest.
Can the Borrower Afford the Payment?
Look at the borrower’s income, expenses, and existing debt.
What Happens If a Payment Is Missed?
Understand the lender’s late payment and default policies.
Can the Cosigner Be Released?
Some lenders may offer cosigner release under specific conditions, but this is not available with every loan.
If release is possible, understand exactly what requirements must be met and whether the lender provides it automatically or only after an application and review.
Should You Agree to Cosign a Personal Loan?
Cosigning is a personal financial decision that should be considered carefully.
The potential benefit is that the borrower may gain access to financing they might not qualify for alone or may potentially receive different loan terms.
The potential risk is that the cosigner may become responsible for repayment if the borrower does not meet their obligations.
Because the loan can affect the cosigner’s finances and credit profile, the decision should not be based solely on trust or family relationships.
A cosigner should understand the loan terms, consider their own financial situation, and be prepared for the possibility that they may need to make payments.
Common Mistakes to Avoid
One common mistake is cosigning without reading the loan agreement.
Another is assuming that the borrower will always make payments on time.
Potential cosigners should also avoid assuming that cosigning has no effect on their ability to borrow later.
Finally, do not rely on verbal promises about when or how the cosigner will be removed from the loan. If a lender offers a release option, review the official requirements and documentation.
Final Thoughts
A personal loan cosigner agrees to share responsibility for a loan if the primary borrower does not meet the repayment obligations. A cosigner may help a borrower qualify for financing, but the arrangement also creates financial and credit responsibilities for the cosigner.
Before signing, both parties should understand the interest rate, APR, fees, monthly payment, loan term, total repayment amount, and consequences of missed payments.
A cosigner should also consider whether they could afford the loan payments if the primary borrower became unable to pay.
Understanding these responsibilities in advance can help both the borrower and cosigner make a more informed decision about whether a cosigned personal loan fits their financial circumstances.

