
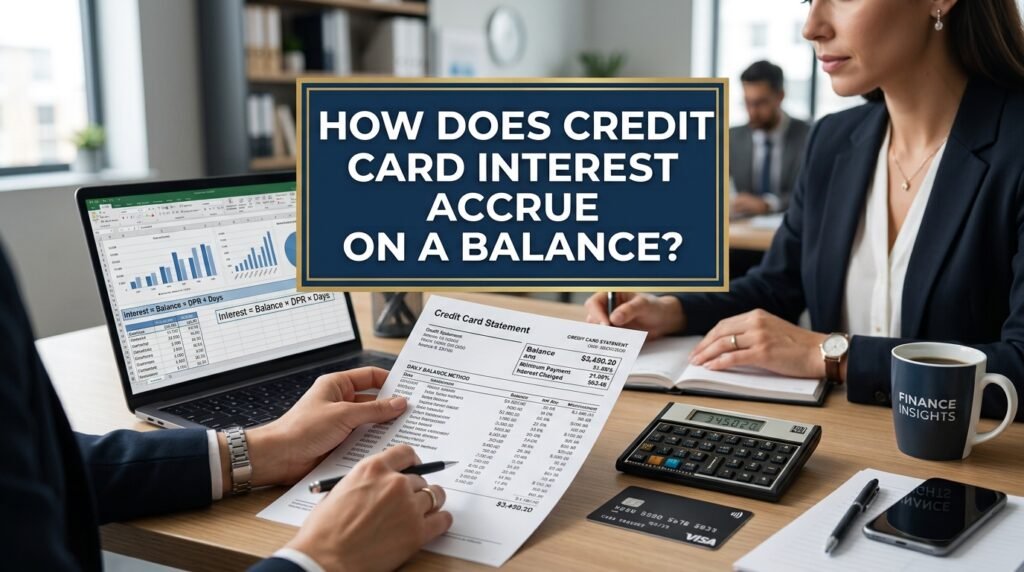
Credit card interest can make borrowing more expensive when you carry a balance from one billing cycle to another. Unlike a fixed personal loan, where you generally make scheduled payments over a set period, a credit card gives you revolving credit that can continue to change as you make purchases and payments.
Understanding how credit card interest accrues can help you see why a balance may take longer to repay than expected. Your APR, daily balance, payments, new purchases, and grace period can all affect how much interest you pay.
What Is Credit Card Interest?
Credit card interest is the cost of borrowing money through your credit card. It is generally expressed as an annual percentage rate, or APR.
For example, suppose your credit card has a 24% APR. That does not usually mean the issuer simply adds 24% to your balance once per year. Credit card interest is commonly calculated using a periodic rate, often based on a daily rate, according to the terms of the account.
This means interest can accrue over individual days when you carry a balance.
The exact calculation method can vary by card issuer and agreement, so always check your cardholder terms.
How Does Credit Card Interest Accrue?
Many credit cards calculate interest using a daily periodic rate.
A simplified daily rate can be estimated by dividing the annual APR by 365.
For example, with a 24% APR:
24% ÷ 365 = approximately 0.0658% per day
If your balance were $2,000, a simplified one-day interest calculation would be:
$2,000 × 0.000658 = approximately $1.32
This is only an illustration. Your actual interest charge can differ because issuers may use specific methods for calculating average daily balances, transaction timing, fees, payments, and other account activity.
What Is an Average Daily Balance?
Some credit card issuers use an average daily balance method to calculate interest.
Under this approach, the issuer considers your balance on each day of the billing cycle and calculates an average.
For example, suppose your balance is:
- $1,000 for 10 days
- $1,500 for 10 days
- $2,000 for 10 days
The average daily balance would be:
($1,000 × 10 + $1,500 × 10 + $2,000 × 10) ÷ 30
That equals:
$45,000 ÷ 30 = $1,500
The issuer would then apply the applicable periodic interest rate to the balance according to the card’s terms.
This is why the timing of purchases and payments can affect the interest calculation.
What Is a Credit Card Grace Period?
A grace period is a period during which you may be able to avoid interest on new purchases if you meet the requirements in your credit card agreement.
For many cards, you can avoid interest on purchases by paying the full statement balance by the due date.
However, grace-period rules can vary, and they may not apply to every type of transaction.
For example, cash advances and balance transfers can have different interest rules.
If you regularly pay your statement balance in full, understanding your grace period can be particularly important.
What Happens When You Carry a Balance?
When you do not pay the required amount in full and your account terms allow interest to accrue, the unpaid balance can generate interest.
Suppose you have a $3,000 balance and your card has a 24% APR. If you continue carrying the balance, interest charges can add to the amount you owe.
If you make only a small payment while continuing to make new purchases, the balance may decline slowly.
This is why the amount you pay each month can have a major effect on how quickly you become debt-free.
You can learn more about this in Credit Card Minimum Payment vs. Full Payment: What It’s Really Costing You, which explains how payment amounts can affect repayment time and total interest costs.
Does Interest Accrue on New Purchases?
It depends on your account status and the terms of your credit card.
If you have a grace period and pay your statement balance in full by the due date, you may avoid interest on eligible new purchases.
However, if you are carrying a balance and have lost your grace period, new purchases may begin accruing interest according to the card’s terms.
This can make it harder to reduce debt because you are paying down an existing balance while potentially adding new interest-bearing purchases.
How Do Payments Affect Interest?
Making payments can reduce your outstanding balance and potentially reduce future interest charges.
For example, suppose your balance is $4,000 and you make a $1,000 payment. Assuming no new purchases or other charges, your balance would decrease to approximately $3,000.
A lower balance generally means less interest can accrue in future periods.
However, the exact timing and application of your payment can affect how interest is calculated.
This is another reason paying earlier or paying more than the minimum can make a difference when you are carrying credit card debt.
What Happens If You Only Pay the Minimum?
The minimum payment is generally the smallest amount your credit card issuer requires you to pay by the due date to keep the account current.
Paying only the minimum can leave a large portion of the balance unpaid.
For example, if you owe $3,000 and your required minimum payment is relatively small, the remaining balance can continue generating interest according to your account terms.
As interest accumulates, your debt can take much longer to repay.
If you continue making new purchases, repayment can take even longer.
This is why it is useful to understand not just the minimum payment, but also the total balance and APR.
How Does APR Affect Interest Accumulation?
Your APR is one of the most important factors affecting the cost of carrying a credit card balance.
Generally, a higher APR means more interest can accrue on the same balance than with a lower APR.
For example, consider two cards with the same $5,000 balance:
- Card A: 18% APR
- Card B: 28% APR
Assuming all other factors are the same, the card with the 28% APR would generally have higher interest costs.
However, your actual interest depends on the issuer’s calculation method, daily balances, payments, and other account terms.
When comparing credit cards, do not look only at rewards or introductory offers. Consider the regular APR if you expect to carry a balance.
What Is Promotional APR?
Some credit cards offer a temporary promotional APR on purchases or balance transfers.
For example, a card may offer 0% APR on eligible purchases for a specified introductory period.
During the promotional period, qualifying balances may not accrue regular interest. However, you still generally need to make the required minimum payments.
Once the promotional period ends, the regular APR may apply to the remaining eligible balance.
You can learn more about this in Credit Card Promotional APR: How Does It Work?.
Can Interest Be Charged on Interest?
Credit card interest can effectively increase the amount on which future interest is calculated when unpaid charges become part of the balance, depending on the issuer’s calculation method and applicable terms.
For example, if interest is added to your account balance and you do not pay it, the next interest calculation may be based on the higher balance.
This is one reason carrying a balance for a long time can become expensive.
The effect becomes more noticeable when the APR is high and payments are relatively small.
How Can You Reduce Credit Card Interest Costs?
There are several ways to potentially reduce the amount of interest you pay.
Pay the Statement Balance in Full
When your card offers a grace period and you meet its requirements, paying the full statement balance by the due date can help you avoid interest on eligible purchases.
Pay More Than the Minimum
If you cannot pay the full balance, paying more than the minimum can reduce the balance faster.
Avoid New Purchases While Paying Down Debt
Adding new charges while trying to repay an existing balance can slow your progress.
Compare Lower-APR Options
Depending on your credit profile and available offers, another credit card or debt-consolidation option may have a lower interest rate.
Consider a Balance Transfer
A balance transfer card may offer a promotional APR for eligible transferred debt. However, fees and promotional expiration dates need to be considered carefully.
Final Thoughts
Credit card interest generally accrues according to the APR and the issuer’s calculation method. Many cards use daily calculations, which means your balance and payment activity can influence how much interest you ultimately pay.
Paying your statement balance in full can help you avoid interest on eligible purchases when your card’s grace-period requirements are met. If you carry a balance, making larger payments and limiting new charges can help reduce the amount of debt that continues generating interest.
Before using a credit card for ongoing borrowing, understand the APR, grace period, fees, promotional terms, and payment requirements. Knowing how interest works can make it easier to manage your balance and avoid unnecessary borrowing costs.
Frequently Asked Questions
How often does credit card interest accrue?
Credit card interest is commonly calculated daily, although the exact method depends on the card issuer and account agreement.
Does credit card interest accrue every day?
Many credit cards use a daily periodic rate, meaning interest can accrue based on the balance each day. Check your card agreement for the exact calculation method.
Can I avoid credit card interest?
You may be able to avoid interest on eligible purchases by paying your full statement balance by the due date when your card provides a grace period and you meet its requirements.
Does paying more than the minimum reduce interest?
Generally, paying more reduces your outstanding balance faster, which can reduce future interest charges.
Does a higher APR mean more interest?
Generally, yes. If two cards have the same balance and other conditions, the card with the higher APR will generally have higher interest costs.
Do new purchases accrue interest immediately?
Not always. If you have a grace period and meet its requirements, eligible purchases may not accrue interest. If you are carrying a balance or the transaction is subject to different terms, interest may apply according to your card agreement.

