How Personal Loans Affect Your Credit Score (Short-Term Dip vs Long-Term Gain)
You take out a personal loan to consolidate credit card debt, feeling good about the plan, and then your credit score dips a few points the following month. That’s the personal loan credit impact most people don’t expect: a short-term cost followed by a longer-term benefit, and the two can look contradictory if you don’t understand the mechanics behind them.
The short version is that this impact typically starts with a small, temporary dip, followed by a gradual improvement if you manage the loan responsibly. Here’s exactly what to expect at each stage, and how to make the process work in your favor.
The Personal Loan Credit Impact in the First Few Months
When you apply for a personal loan, the lender performs a hard credit inquiry to evaluate your application. According to credit scoring data from myFICO, a single hard inquiry typically lowers your FICO Score by around five points or less, and this effect is usually temporary, fading within several months.
Beyond the inquiry itself, opening a brand-new account also affects two other factors: it slightly lowers the average age of your credit accounts, and it adds a new balance to your total amount owed. Both are part of the early impact, and both are small, mechanical effects, not signs that anything is wrong with your credit management.
Why This Early Dip Doesn’t Reflect Your Creditworthiness
It’s worth understanding that this initial dip isn’t a penalty for poor financial behavior. It’s simply how scoring models treat any new account, new information means the model hasn’t yet seen how you’ll manage it, so it temporarily treats the account as an unknown. This early stage is procedural, not a reflection of your actual reliability as a borrower.
How Personal Loan Credit Impact Shifts Over the Following Year
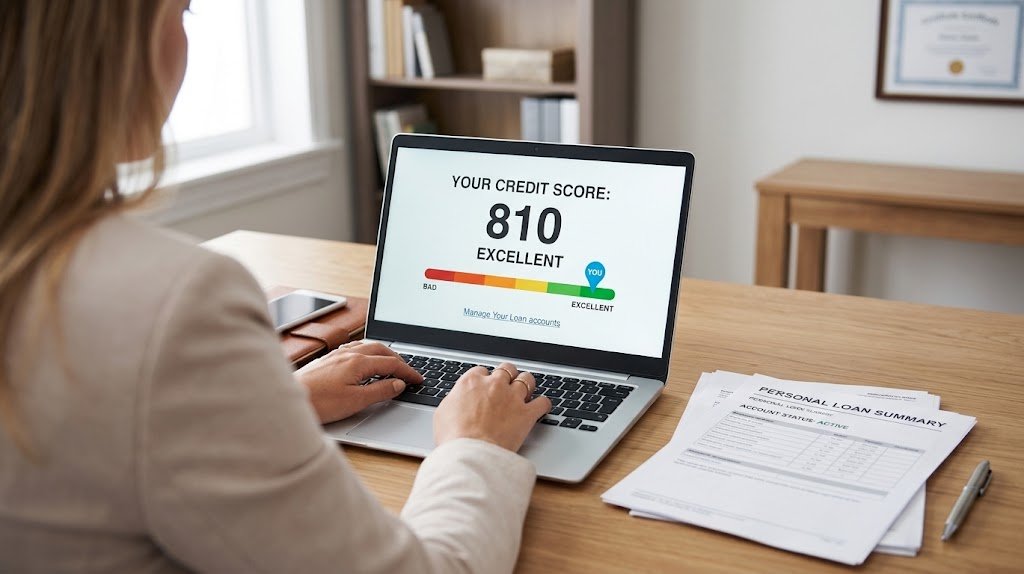
This is where the picture turns in your favor, assuming you make payments on time. Payment history is the single largest factor in most credit scoring models, and every on-time payment on your new loan actively builds positive history, turning that early dip into a net positive over time.
There’s also a structural benefit: adding an installment loan (fixed payments over a set term) to a credit file that previously consisted only of revolving credit, like credit cards, can improve your credit mix. Scoring models tend to favor a mix of account types, which adds another layer of benefit beyond payment history alone.
The Utilization Benefit Behind Long-Term Personal Loan Credit Impact
If you used the loan specifically to consolidate high-interest credit card debt, there’s often an additional benefit: your credit card utilization ratio drops significantly once those balances are paid down, even though your total debt hasn’t necessarily decreased by much yet. Since utilization carries substantial weight in most scoring models, this shift alone can meaningfully offset the initial dip, making the overall effect positive much sooner than people expect.
A Realistic Timeline of the Credit Impact
Months 1 to 3: Expect a small dip, typically in the single digits, from the hard inquiry and the new account lowering your average account age. This is the expected pattern in the earliest stage.
Months 4 to 12: As on-time payments accumulate and the initial inquiry’s effect fades, your score often begins recovering and can move higher than where it started, particularly if the loan reduced high credit card utilization.
Year one and beyond: With a full year or more of consistent, on-time payments, the net result typically becomes clearly positive, contributing to both payment history and credit mix.
This is a general pattern, not a guarantee of any specific point movement, since individual results depend on your full credit profile and payment behavior.
What Can Make the Personal Loan Credit Impact More Negative
Missing payments. This is by far the biggest risk. A payment 30 or more days late can be reported to credit bureaus and significantly damage your score, staying on your credit report for up to seven years.
Applying for multiple loans in a scattered pattern. Spreading loan applications out over several months, rather than comparing offers within a short rate-shopping window, can worsen the outcome by generating multiple separate hard inquiries rather than one consolidated one.
Taking on more total debt than you can manage. Since amounts owed factor heavily into most scores, a large new loan balance, especially one that isn’t offset by paying down other debt, can weigh on your score more than a smaller one would.
Not addressing why your score dropped after paying off other debt. Sometimes people are surprised their score dipped even after paying something off. Understanding why your credit score dropped after paying off a balance can clarify whether the loan itself, or another factor entirely, is behind the change.
How to Manage Personal Loan Credit Impact Responsibly
Set up autopay immediately. The single biggest lever in your long-term outcome is on-time payment history. Automating payments removes the risk of an accidental miss.
Avoid applying for other new credit shortly afterward. Giving your score time to recover from the initial inquiry before opening additional accounts helps keep your credit mix and inquiry history looking stable.
Use the loan for its intended purpose. If you took out the loan to consolidate credit card debt, actually paying down those balances (rather than running them back up) is what delivers the long-term benefit.
Check your credit report periodically. Confirming the loan is being reported accurately, and that your other accounts, like whether you’re managing multiple credit cards vs. one card well, helps you catch any errors early that could distort the picture.
Don’t panic over the early dip. Understanding that a temporary decrease is a normal, expected part of the process can help you avoid overreacting, like closing the loan early or making financial decisions based on a short-term score movement.
Practical Takeaways
- The personal loan credit impact typically starts with a small, temporary dip in the first few months due to the hard inquiry and new account.
- On-time payments over the following months and years are the biggest factor in turning that dip into a long-term gain.
- Using a personal loan to pay down credit card balances can improve your utilization ratio, offsetting much of the initial negative effect.
- Missing even one payment can cause significant, long-lasting damage, far outweighing the temporary dip from the inquiry itself.
- The overall outcome depends far more on your repayment behavior than on the loan itself.
Final Thoughts
The short-term dip that comes with a new personal loan is a normal, expected part of how credit scoring works, not a sign that something has gone wrong. What actually determines the long-term personal loan credit impact is how consistently you manage the payments afterward. Handled responsibly, a personal loan is one of the more reliable ways to build a stronger, more diverse credit profile over the following year and beyond.
This article is for general educational purposes and isn’t personalized financial advice. Credit scoring impacts vary based on your individual credit history, so consider your own financial situation before taking out a personal loan.