
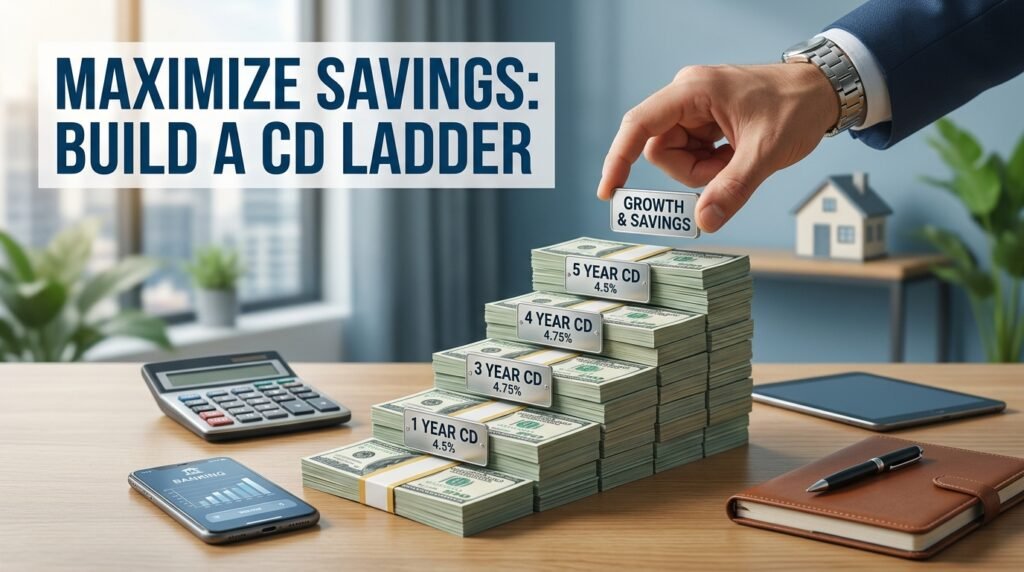
Saving money is not only about how much you put aside. Where you keep your savings can also affect how much interest you earn and how easily you can access your money. Certificates of deposit, commonly known as CDs, can provide a fixed interest rate for a specific period, but locking all your money into one CD term may create a problem when you need access to cash.
A CD ladder is one strategy that can help solve this issue. Instead of putting all your savings into a single CD with one maturity date, you divide the money among several CDs with different maturity dates. This approach can provide a combination of predictable interest earnings and regular access to portions of your savings.
What Is a CD Ladder?
A CD ladder is a savings strategy that involves opening multiple certificates of deposit with different maturity dates.
For example, instead of putting $10,000 into one five-year CD, you could divide the money into several smaller CDs with different terms.
A simple ladder might include:
- $2,000 in a one-year CD
- $2,000 in a two-year CD
- $2,000 in a three-year CD
- $2,000 in a four-year CD
- $2,000 in a five-year CD
As each CD matures, you can decide what to do with the money. You might use the funds, move them into a new CD, or continue the ladder by reinvesting the proceeds into another longer-term CD.
The exact structure depends on your savings goals, interest rates, cash needs, and tolerance for having money locked away.
How Does a CD Ladder Work?
The basic idea is to spread your money across different maturity dates instead of locking everything away at the same time.
Suppose you have $15,000 available for medium-term savings. You could divide it into five $3,000 CDs with maturities spaced one year apart.
After the first year, the first CD matures. You now have access to that $3,000 plus any interest earned.
If you do not need the money, you could reinvest it into a new five-year CD. The following year, another CD matures, giving you another opportunity to access or reinvest your savings.
Over time, this can create a repeating cycle of CD maturities.
The main benefit is that you do not have to wait for one long-term CD to mature before getting access to any of your money.
Why Do People Use CD Ladders?
One reason people use CD ladders is to balance interest earnings with liquidity.
Longer-term CDs may offer different rates from shorter-term CDs, although rates vary by institution and market conditions. By spreading money across several terms, you avoid having to make one large decision about where to lock all your savings.
A CD ladder can also reduce the risk of having all your money mature at exactly the same time.
For example, if you put $20,000 into one five-year CD, you may have to make a large reinvestment decision when that CD matures. With a ladder, different portions of your savings mature at different times.
This can make managing medium-term savings more structured.
CD Ladder Example
Imagine you have $10,000 that you do not expect to need immediately.
You could create a five-step ladder:
| CD | Amount | Term |
| CD 1 | $2,000 | 1 year |
| CD 2 | $2,000 | 2 years |
| CD 3 | $2,000 | 3 years |
| CD 4 | $2,000 | 4 years |
| CD 5 | $2,000 | 5 years |
After one year, CD 1 matures.
If you need the money, you can withdraw it. If you do not need it, you could potentially reinvest it into another five-year CD.
The same process continues as each CD reaches maturity.
This means that after the initial setup period, you could potentially have a CD maturing every year.
The actual interest earned will depend on the rates offered when each CD is opened and the terms of the accounts.
Benefits of a CD Ladder
More Regular Access to Savings
A CD ladder can provide more frequent access to portions of your money than putting everything into one long-term CD.
This can be useful for people who want predictable maturity dates without keeping all their savings in a low-yield account.
However, a CD ladder should not replace money that you may need immediately.
For unexpected expenses, an accessible savings account may be more appropriate. Our recently published guide on an emergency savings account and where to keep it explains why liquidity and accessibility matter when building emergency savings.
Potentially More Predictable Interest
When you open a CD with a fixed rate, the interest rate generally remains fixed for the agreed term, subject to the account’s terms.
This can make it easier to estimate how much interest a particular CD may earn before maturity.
The rates available for future CDs, however, can be different. A ladder does not guarantee that future CDs will offer the same rate as your existing accounts.
Reduced Reinvestment Timing Risk
A CD ladder spreads maturity dates across multiple periods.
If all your money were in one CD, you might have to reinvest the entire balance at whatever rates are available when that CD matures.
With a ladder, only one portion of the portfolio typically reaches maturity at a time.
This gives you repeated opportunities to evaluate current rates rather than making one large reinvestment decision.
Encourages Structured Saving
A CD ladder can also provide a framework for managing money that you do not need for everyday expenses.
Instead of moving money between accounts without a plan, you can assign specific amounts and maturity dates to different portions of your savings.
This can make medium-term savings easier to organize.
What Are the Disadvantages of a CD Ladder?
A CD ladder is not completely risk-free or suitable for every savings goal.
Limited Access Before Maturity
Most CDs are designed for money that you can leave deposited until the maturity date.
If you withdraw money before maturity, the bank or credit union may charge an early-withdrawal penalty. The specific penalty depends on the institution and account terms.
This is one reason you should avoid placing your entire emergency fund into CDs.
Future Rates May Be Lower
A CD ladder does not guarantee that interest rates will remain attractive.
Suppose you open several CDs when rates are relatively high. When one matures later, the available rate for a new CD could be lower.
You may then have to choose between accepting a lower rate, keeping the money somewhere else, or changing your ladder strategy.
Interest-rate changes can therefore affect your reinvestment decisions. Our guide to how higher interest rates affect your money explains how changes in rates can influence savings products, including CDs.
More Accounts to Manage
Managing multiple CDs requires keeping track of maturity dates, interest rates, account terms, and automatic renewal instructions.
If you forget about a maturity date, the institution may automatically renew the CD according to its renewal terms.
Keeping a simple record or calendar reminder can help you avoid missing important dates.
CD Ladder vs. Keeping Money in a Savings Account
A savings account and a CD serve different purposes.
A savings account generally provides easier access to your money, while a CD typically requires you to commit the funds for a specified period.
A CD ladder attempts to combine some of the structure of CDs with more regular access to portions of the money.
For example, an emergency fund may need to remain highly accessible, while money saved for a future expense several years away may be more suitable for a CD ladder.
The key is matching the account type to the purpose of the money.
CD Ladder and Compound Interest
Interest can also contribute to the long-term growth of savings.
When interest remains in an account and becomes part of the balance, it may generate additional interest over time, depending on the product and how interest is handled.
Our recently published guide on compound interest and how it grows savings explains how earning interest on previous interest can contribute to long-term savings growth.
With CDs, you should review whether interest is paid into the CD, transferred to another account, or handled according to another arrangement. The terms can differ between institutions.
How to Build a CD Ladder
If you are considering a CD ladder, start by identifying money that you are unlikely to need immediately.
Next, decide how many maturity periods you want.
For example, you could create a three-year ladder with CDs maturing every year, or a five-year ladder with annual maturity dates.
Then compare available CDs based on:
- Interest rate and APY
- Term length
- Minimum deposit
- Early-withdrawal penalty
- Automatic renewal terms
- Deposit insurance
- Interest payment options
Do not choose a CD based solely on its advertised rate. The account’s full terms can affect how useful the product is for your financial goals.
Should You Use a CD Ladder for Emergency Savings?
A CD ladder may not be ideal for your entire emergency fund.
Emergency money should generally be accessible when an unexpected expense occurs. A CD may restrict access or impose an early-withdrawal penalty.
Instead, some savers may keep their emergency reserve in an accessible savings account while using a CD ladder for money intended for medium-term goals.
For example, you might keep your emergency savings in an accessible account and use separate CDs for money you expect to leave untouched for several years.
This separation can help prevent an unexpected expense from forcing you to break a CD early.
Final Thoughts
A CD ladder is a strategy for spreading savings across CDs with different maturity dates. Instead of locking all your money into one CD term, you create several maturity points that can provide more regular opportunities to access or reinvest your savings.
The strategy can offer structure and predictable interest on individual CDs, but it also comes with limitations. Early withdrawals may result in penalties, future CD rates can change, and managing multiple accounts requires attention.
Before creating a CD ladder, separate money you may need immediately from money you can leave untouched for longer periods. Compare rates, terms, penalties, and account conditions, then choose a structure that matches your savings goals and liquidity needs.

