
Bonds are often considered more predictable investments than stocks because they can provide scheduled interest payments and a defined maturity date. However, bond prices can still move significantly when interest rates change.
One of the most useful concepts for understanding this relationship is bond duration.
Bond duration helps investors estimate how sensitive a bond or bond portfolio may be to changes in interest rates. In general, bonds with higher duration tend to experience larger price changes when interest rates move, while bonds with lower duration tend to be less sensitive.
Understanding duration can therefore help investors evaluate interest rate risk before buying individual bonds or bond funds.
What Is Bond Duration?
Bond duration is a measure of a bond’s sensitivity to changes in interest rates.
It is expressed in years, but it should not simply be confused with the bond’s maturity.
For example, a bond may have a maturity of 10 years but a duration of approximately 8 years. The maturity tells you when the bond’s principal is scheduled to be repaid, while duration provides an estimate of how sensitive its price is to interest rate changes.
Duration considers the timing of a bond’s expected cash flows, including interest payments and the final repayment of principal.
The earlier an investor receives cash flows, generally the lower the duration tends to be.
Why Does Bond Duration Matter?
Interest rates and bond prices generally move in opposite directions.
When market interest rates rise, existing bonds with lower coupon rates can become less attractive compared with newly issued bonds offering higher rates. As a result, the market price of existing bonds may fall.
When market interest rates decline, existing bonds with higher coupon rates can become more attractive, which can cause their market prices to rise.
Duration helps investors estimate how large that price movement could be.
For example, a bond with a duration of 2 years may generally be less sensitive to an interest rate change than a bond with a duration of 10 years.
This makes duration especially important for investors who hold bond funds or may need to sell bonds before maturity.
How Does Duration Measure Interest Rate Risk?
A common approximation is that a bond’s percentage price change is roughly equal to its duration multiplied by the change in interest rates, with the direction reversed.
For example, suppose a bond has a duration of 5 years.
If market interest rates rise by 1 percentage point, the bond’s price could decline by approximately 5%, all else being equal.
If interest rates fall by 1 percentage point, the bond’s price could increase by approximately 5%.
This is only an approximation. Actual price changes can differ because of factors such as convexity, changes in credit risk, cash flows, and the size of the interest rate movement.
Still, the basic relationship provides a useful way to understand interest rate sensitivity.
Duration vs. Maturity
Duration and maturity are related but different concepts.
Maturity refers to the date when the bond’s principal is scheduled to be repaid.
Duration measures the weighted average timing of the bond’s cash flows and provides an indication of interest rate sensitivity.
Consider two bonds that both mature in 10 years.
One may pay a relatively high coupon, while the other pays a lower coupon.
The higher-coupon bond provides more cash to the investor earlier through its interest payments. Because more of its cash flows arrive sooner, its duration may be lower.
The lower-coupon bond may have a higher duration because more of the investment’s value is tied to the final principal repayment.
Therefore, two bonds with the same maturity can have different levels of interest rate risk.
What Factors Affect Bond Duration?
Several characteristics can influence a bond’s duration.
Coupon Rate
Generally, bonds with higher coupon rates tend to have lower duration than otherwise similar bonds with lower coupon rates.
A higher coupon means the investor receives more cash earlier, reducing the weighted average timing of the cash flows.
Time to Maturity
Longer-maturity bonds generally have higher duration than shorter-maturity bonds, although the exact relationship depends on the coupon and other characteristics.
The longer investors must wait for a significant portion of their principal to be returned, the more sensitive the bond may be to interest rate changes.
Yield
Changes in a bond’s yield can also affect its duration.
As yields change, the present value of future cash flows changes, which can alter the duration calculation.
Cash Flow Structure
Bonds with different payment structures can have different durations even when they have similar maturities.
Zero-coupon bonds, for example, make no regular interest payments. Instead, the investor receives the principal at maturity. Because there are no earlier coupon payments, their duration is generally equal to their maturity.
What Is Modified Duration?
Modified duration is commonly used to estimate how much a bond’s price may change when its yield changes.
For example, if a bond has a modified duration of 6, a 1 percentage point increase in yield could correspond to an approximate 6% decline in price.
Similarly, a 1 percentage point decrease in yield could correspond to an approximate 6% increase in price.
The estimate becomes less precise as interest rate changes become larger because the relationship between price and yield is not perfectly linear.
This is where convexity becomes useful.
What Is Convexity?
Convexity describes how the relationship between a bond’s price and yield changes as interest rates move.
Duration provides a first approximation of price sensitivity, but bond prices do not move in a perfectly straight line in response to changing yields.
Convexity can help investors understand this curvature.
For relatively small interest rate movements, duration may provide a useful estimate. For larger changes, considering convexity can produce a more accurate understanding of potential price movements.
Professional bond portfolio managers often consider both duration and convexity when evaluating interest rate risk.
Why Bond Duration Matters for Bond Funds
Duration is particularly important when investing in bond funds.
A bond fund can hold dozens, hundreds, or even thousands of individual bonds. Instead of looking at the duration of one specific bond, investors can examine the fund’s portfolio duration.
For example, a short-duration bond fund may generally be less sensitive to interest rate movements than a long-duration bond fund.
This does not mean a short-duration fund cannot lose money.
Bond funds can be affected by interest rate changes, credit risk, market conditions, and other factors.
Investors should therefore review the fund’s duration alongside its credit quality, expenses, holdings, yield, and investment strategy.
What Happens When Interest Rates Rise?
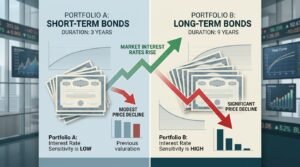
When interest rates rise, bonds with higher duration generally experience greater price declines than bonds with lower duration, all else being equal.
Imagine two bond portfolios.
Portfolio A has a duration of 3 years.
Portfolio B has a duration of 9 years.
If market yields rise significantly, Portfolio B would generally be expected to experience a larger percentage price decline because of its greater interest rate sensitivity.
This does not necessarily mean the higher-duration portfolio is a poor investment.
An investor with a long time horizon may be willing to accept greater short-term price fluctuations in exchange for the characteristics of longer-duration bonds.
The important point is understanding the trade-off.
What Happens When Interest Rates Fall?
The relationship works in the opposite direction when interest rates decline.
Higher-duration bonds generally have greater potential price appreciation when yields fall, all else being equal.
For example, a bond with a duration of 8 years may experience a larger price increase from a given decline in yields than a bond with a duration of 2 years.
This is one reason duration can work both ways.
Higher duration means greater sensitivity, not simply greater downside risk.
How Inflation Can Affect Bond Investors
Inflation is another important factor when evaluating bonds.
If inflation rises, central banks may respond by changing interest rates. Higher rates can put downward pressure on existing bond prices.
Inflation can also reduce the purchasing power of future interest payments and principal repayments.
For example, receiving $1,000 several years from now may not provide the same purchasing power if prices have increased substantially.
Investors interested in protecting purchasing power can learn more from our guide on how to protect your money from inflation in 2026.
Duration and Your Investment Time Horizon
An investor’s time horizon can influence how important duration becomes.
If you plan to hold an individual bond until maturity and the issuer makes all required payments, temporary market price movements may be less important because the bond is scheduled to repay its face value at maturity.
However, this does not eliminate risk.
The issuer could default, and inflation can reduce the purchasing power of the payments you receive.
Bond funds work differently because they generally do not have a single maturity date for the entire portfolio. The fund continuously buys and sells securities according to its strategy.
This makes duration an especially useful metric for understanding a bond fund’s interest rate sensitivity.
How Can Investors Compare Bond Funds?
When comparing bond funds, duration is only one factor to consider.
You may also want to review:
- Average maturity
- Credit quality
- Expense ratio
- Yield
- Fund holdings
- Investment strategy
- Geographic exposure
- Government vs corporate bonds
- Historical volatility
A fund with a low expense ratio may have an advantage in terms of ongoing costs, but fees are only one part of the overall investment analysis.
Similarly, a higher yield may come with additional credit or interest rate risk.
Understanding the characteristics of the entire portfolio is more useful than focusing on one number.
Does a Shorter Duration Mean Lower Risk?
Not necessarily.
Shorter duration generally means lower sensitivity to interest rate changes, but it does not eliminate other investment risks.
For example, a short-duration corporate bond fund could still be exposed to credit risk if companies have financial difficulties.
A bond issued by a financially weak borrower may carry greater default risk than a government security, even if both have similar durations.
Investors should therefore distinguish interest rate risk from credit risk.
Duration primarily helps measure sensitivity to interest rate changes. It does not provide a complete measurement of every risk associated with a bond.
Bond Duration and Savings Alternatives
Investors comparing bonds with savings products should also consider liquidity and access to their money.
For example, a savings account can provide relatively easy access to cash, while a bond’s market value can fluctuate when interest rates change.
The interest rate on a savings account can also change over time. Our recent guide comparing high-yield savings accounts with regular savings accounts explains how APYs, access, fees, and account features can differ.
This comparison can be useful when deciding which portion of your money should remain in cash and which portion may be suitable for longer-term investments.
Can Duration Change Over Time?
Yes.
A bond’s duration can change as it gets closer to maturity.
As time passes and coupon payments are made, the timing of the remaining cash flows changes.
For bond funds, duration can also change because the fund manager buys and sells securities, bonds mature, and market conditions change.
Therefore, an investor should not assume that a fund’s duration will remain exactly the same forever.
Checking the fund’s current information can provide a more accurate picture of its interest rate sensitivity.
Common Mistakes When Looking at Bond Duration
One common mistake is assuming duration and maturity are the same.
They are not.
Another mistake is assuming higher duration is always bad.
Higher duration simply means greater sensitivity to interest rate changes. Whether that sensitivity is appropriate depends on the investor’s objectives and risk tolerance.
It is also a mistake to use duration as the only measure of bond risk.
Credit quality, liquidity, inflation, fees, and the structure of the investment can also affect potential outcomes.
Finally, investors should remember that market value matters if they need to sell a bond before maturity.
Final Thoughts
Bond duration is an important measure of interest rate risk.
It helps investors estimate how sensitive a bond or bond portfolio may be when market interest rates change. Generally, higher-duration bonds experience larger price movements when rates move, while lower-duration bonds tend to be less sensitive.
Duration is different from maturity. Maturity tells you when the bond is scheduled to repay its principal, while duration focuses on the timing of cash flows and interest rate sensitivity.
For investors evaluating individual bonds or bond funds, understanding duration can provide useful context when comparing different investments.
However, duration should not be considered in isolation. Credit quality, yield, fees, inflation, liquidity, maturity, and investment objectives all matter.
By understanding these factors, investors can better evaluate how changing interest rates may affect the value and behavior of their bond investments.

