Why Your Credit Score Varies Across Apps: FICO vs VantageScore Explained
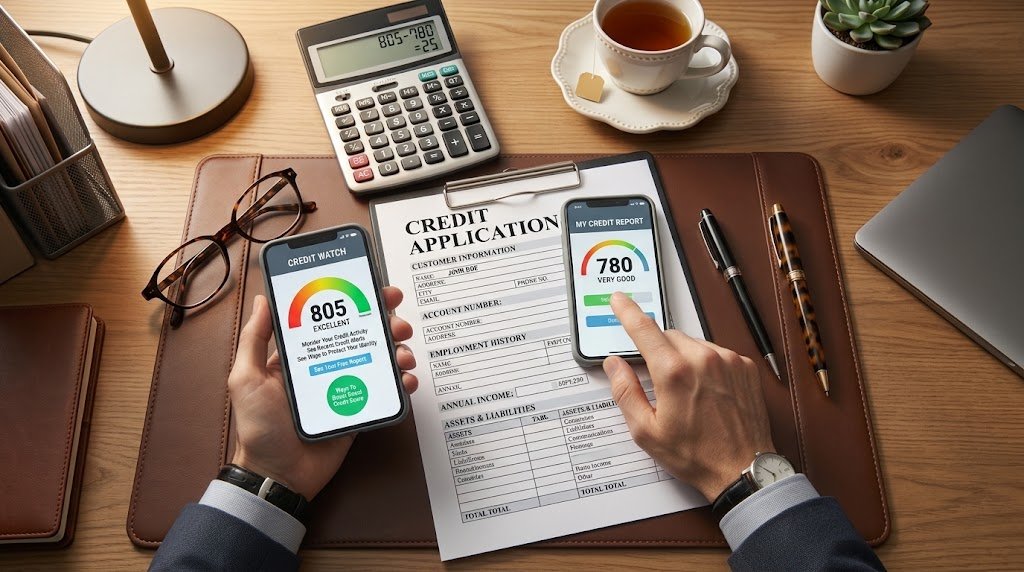
You check your credit score on your bank’s app and see 712. You open a free credit monitoring app the same afternoon and see 734. Neither app is broken, and neither number is wrong. The gap comes down to FICO vs VantageScore, the two major scoring models behind almost every credit score you’ll ever see, and they don’t always agree.
If you’ve ever wondered why your “credit score” seems to change depending on where you look, understanding FICO vs VantageScore is the missing piece. Here’s what each model actually measures, why they land on different numbers from the same credit report, and which one actually matters when you apply for credit.
FICO vs VantageScore: What Each One Actually Is
A FICO Score comes from the Fair Isaac Corporation, the company that created the modern credit scoring system back in 1989. Each of the three major credit bureaus (Equifax, Experian, and TransUnion) generates its own version of your FICO Score using slightly different underlying data.
VantageScore, by contrast, was created jointly by those same three bureaus in 2006, specifically to offer an alternative to FICO. It uses a different formula, and it’s the model behind most of the free credit scores you see in banking apps, credit card issuer dashboards, and free monitoring services like Credit Karma.
Both models produce a number between 300 and 850. Both use your credit report as the raw input. But because they weigh the same information differently, FICO vs VantageScore routinely produces different scores from identical data.
Why FICO vs VantageScore Produces Different Numbers From the Same Report
The core reason your score shifts depending on which model generated it comes down to weighting. Payment history matters most to both FICO and VantageScore, but beyond that, the models diverge. VantageScore’s newer models (3.0 and 4.0) weigh payment history at roughly 40%, while FICO’s widely used Score 8 and Score 9 models weigh it closer to 35%. Credit utilization gets about 30% weight under FICO but closer to 20% under VantageScore. Length of credit history carries more weight in VantageScore’s formula than it does in FICO’s.
These aren’t small technical differences. A CFPB analysis comparing consumer-facing and creditor-purchased credit scores found that even scores generated using the same underlying data can diverge meaningfully once you account for different scoring models, different score versions, and different snapshots in time of a person’s credit report. That’s the structural reason FICO vs VantageScore rarely produces an identical number, even on the exact same day.
How Score Ranges Differ Between FICO and VantageScore
Another source of confusion in the FICO vs VantageScore comparison is that “good” doesn’t mean the same thing on both scales, even though both run from 300 to 850.
FICO score ranges:
- Exceptional: 800–850
- Very Good: 740–799
- Good: 670–739
- Fair: 580–669
- Poor: 300–579
Compare that to VantageScore’s tiers, and the FICO vs VantageScore gap becomes obvious:
VantageScore ranges:
- Superprime (Excellent): 781–850
- Prime (Good): 661–780
- Near Prime (Fair): 601–660
- Subprime (Poor): 300–600
Notice that a 660 falls into VantageScore’s “good” category but lands in FICO’s “fair” range. Someone checking a free app might see “good credit” while a mortgage lender pulling a FICO Score sees something closer to “fair.” That mismatch, a direct result of FICO vs VantageScore using different tier labels for the same score, is one of the more common reasons people feel blindsided when a loan offer doesn’t match what their credit app told them to expect.
Why VantageScore Can Score You Sooner Than FICO
One meaningful practical difference between FICO and VantageScore: VantageScore can generate a score with as little as one month of credit history and a single reported account. FICO traditionally requires at least six months of credit activity and at least one account reporting before it can produce a score. If you’re just starting to build credit from scratch, you may see a VantageScore appear on a monitoring app well before you’re eligible for a FICO Score at all.
Which Score Actually Matters When You Apply for Credit
This is the part of the FICO vs VantageScore comparison that trips people up most. FICO Scores are used in the vast majority of actual lending decisions, particularly for mortgages, auto loans, and most credit card applications. The free score in your banking app, which is usually a VantageScore, is a useful directional tool, but it’s often not the number a lender will actually pull.
This FICO vs VantageScore gap matters most around big financial decisions. If you’re gathering documents for mortgage pre-approval or comparing pre-approval vs. pre-qualification offers, the VantageScore you saw on a free app may not match the FICO Score the lender actually pulls, and that gap can occasionally affect the rate or terms you’re offered. It’s a good reason not to treat a free monitoring score as the final word when you’re about to apply for something significant.
Both Scores Still Move in the Same Direction
Despite their differences, FICO and VantageScore generally agree on direction, even when they disagree on the exact number. Paying down a high balance, avoiding late payments, and keeping older accounts open tend to help both scores similarly. Understanding why your credit score dropped after paying off a balance or how credit card limit increases affect utilization applies to both models, even if the exact point swing differs between FICO and VantageScore.
A Realistic Example of FICO vs VantageScore in Action
Imagine someone with a well-managed credit history: a long track record of on-time payments, moderate credit utilization, and a healthy mix of account types. Their FICO Score might land at 738, comfortably in FICO’s “Good” range. The same credit data, run through a VantageScore 3.0 model, might produce a 758, landing in VantageScore’s “Prime” tier. Neither number is inaccurate. Each simply reflects how that specific model in the FICO vs VantageScore comparison weighs the same underlying information. This is a hypothetical example meant to illustrate how these differences show up in practice, not a guarantee of how any individual’s scores will compare.
Common Mistakes People Make With FICO vs VantageScore
Assuming the free app score is what lenders see. Most consumer apps display a VantageScore because it’s cheaper and easier for companies to license and distribute. Lenders overwhelmingly still pull FICO Scores for actual credit decisions, which is exactly why the FICO vs VantageScore distinction matters.
Panicking over small score differences between apps. A 15 to 25 point gap between your banking app’s VantageScore and a credit card issuer’s FICO-based dashboard is completely normal given how differently the two models weigh the same data. It’s not a sign that something is wrong with your credit report.
Ignoring which factors matter most to each model. Because utilization is weighted more heavily under FICO, someone focused primarily on lowering their VantageScore might miss that paying down balances would move their FICO Score more. If you’re managing multiple credit cards vs. one card, understanding this FICO vs VantageScore weighting difference helps you know which habits move the number that actually matters for your next application.
Not checking your FICO Score before a major application. If you’re about to apply for a mortgage, auto loan, or a card advertising instant approval, it’s worth checking your actual FICO Score, often available for free through your bank or card issuer, rather than relying solely on a VantageScore from a monitoring app.
Confusing score versions within the same model. There isn’t just one FICO Score. FICO Score 8, FICO Score 9, and industry-specific versions like FICO Auto Score can all produce different numbers from the same credit file, adding another layer of variation beyond the basic FICO vs VantageScore divide.
Practical Takeaways on FICO vs VantageScore
- FICO vs VantageScore differences come from how each model weighs the same credit report data, not from errors in either score.
- FICO Scores are used in most actual lending decisions; VantageScore is more common in free consumer apps.
- Score ranges differ between the two models, so a number that looks “good” on the VantageScore scale might land differently on FICO’s scale.
- VantageScore can generate a score sooner than FICO for people with limited credit history.
- Both models generally move in the same direction in response to the same credit habits, even when the exact FICO vs VantageScore numbers differ.
Final Thoughts
Seeing two different numbers for what feels like “your credit score” isn’t a glitch. It’s the natural result of FICO vs VantageScore being two separate, competing models built on overlapping but distinct formulas. Neither one is the single “true” score, but knowing which one a lender is likely to use before a major application can save you from an unpleasant surprise.
If you want the clearest picture, check your FICO Score directly ahead of any major credit decision, and treat the VantageScore in your everyday apps as a useful trend indicator rather than the definitive number. What matters most for your credit health, on-time payments, manageable utilization, and a solid credit history, moves both sides of the FICO vs VantageScore comparison in the same direction over time.
This article is for general educational purposes and isn’t personalized financial advice. For questions about your own credit report or scores, you can also review resources through the Consumer Financial Protection Bureau’s credit reporting guidance.