
Unexpected fees can manifest when you least expect them. A car repair, urgent medical invoice, home renovation hassle, or temporary lack of profits can quickly place strain on your budget. Without financial savings, you may have to depend on credit cards, loans, or assistance from others to cover the fee.
An emergency fund can provide a monetary cushion for these conditions. It is cash set apart for unexpected and vital costs, helping you cope with financial surprises without absolutely disrupting your monthly budget
If you are also working on improving your overall money management, you can explore more personal finance resources at CoreFoxes.
What Is an Emergency Fund?
An emergency fund is a committed amount of money reserved for unexpected fees.
It isn’t like regular financial savings for planned purchases. For example, cash saved for a vacation, a new pc, or vacation purchases isn’t always generally considered emergency savings.
An emergency fund can be useful for conditions consisting of:
- Unexpected car maintenance
- Urgent home maintenance
- Necessary scientific expenses
- Temporary loss of income
- Emergency journey
- Unexpected important bills
- Other big costs that are hard to cover out of your regular profits
The foremost reason is to provide you get entry to to money when a surprising monetary need takes place.
Why Is an Emergency Fund Important?
Without emergency financial savings, an unexpected fee can force you to borrow money.
For instance, think your car suddenly needs a $1,000 repair, and you do not have financial savings to be had. You might place the repair on a credit card and repay the balance over several months. Depending on the card’s interest rate, the final price might be higher than the original repair invoice.
An emergency fund can lessen your need to depend on borrowing while surprising expenses arise.
This turns into in particular essential whilst borrowing fees are excessive. If you want to recognize how borrowing alternatives can range, examine our guide on Personal Loan vs. Credit Card.
How Much Should You Save?
There is no single emergency fund target that works for anybody.
The quantity you need can rely upon your:
- Monthly essential charges
- Income balance
- Housing costs
- Debt bills
- Family responsibilities
- Insurance insurance
- Employment situation
- Personal monetary dreams
If you’re simply getting started, setting a smaller initial purpose can make the process less complicated.
For instance, you can begin with a target of $500 or $1,000. Once you reach that amount, you can hold off on building your fund primarily based on your vital monthly costs.
Some people aim, in the end shop enough to cover several months of important charges. Your personal target ought to reflect your situation instead of virtually following a fixed range.
Step 1: Calculate Your Essential Expenses
The first step is knowing how much you actually need every month.
Start by using listing vital costs along with:
- Rent or mortgage
- Utilities
- Groceries
- Transportation
- Insurance
- Minimum debt bills
- Basic healthcare charges
- Necessary family prices
For instance, if your vital costs general $2,500 in step with month, you could use that to determine how large your emergency fund needs to be.
You do not want to reach your final target without delay. Think of your emergency fund as a monetary aim that you build steadily.
Step 2: Set a Realistic Monthly Savings Goal
After calculating your expenses, decide how a good deal you can simply keep each month.
For instance, saving $one hundred fifty according to month could result in:
- $450 after 3 months
- $900 after six months
- $1,800 after 12 months
The amount does not have to be big. A smaller contribution that you could keep continuously is regularly less difficult to manage than an aggressive target that creates issues someplace else in your budget.
If your earnings change from month to month, you could set up a minimum amount and make contributions more when your income is better.
Step 3: Make Saving Automatic
One of the handiest methods to build an emergency fund is to automate your savings.
You can set up a recurring transfer from your bank account to a separate savings account after receiving your paycheck.
For instance, you may automatically transfer $one hundred or $two hundred every month.
Automation helps make saving a normal financial habit. You do no longer have to recollect to move the cash manually each month.
You can also review your monthly budget regularly to identify expenses that could be reduced. For more help with budgeting, you can explore practical money management and financial tools from CoreFoxes.
Step 4: Keep Emergency Savings Separate
Consider maintaining your emergency fund separate from the account you use for normal spending.
When emergency savings are combined with ordinary spending money, it could be less complicated to by chance use them for non-crucial purchases.
A separate savings account can make the purpose of the cash clearer.
At the same time, the account has to be moderately on hand while a genuine emergency takes place. The intention is to balance accessibility with maintaining the cash break free normal spending.
Step 5: Use Extra Money to Increase Savings
Your regular monthly contribution does not have to be the simplest manner you construct an emergency fund.
When you get hold of additional cash, you may bear in mind putting a portion of it towards your savings goal.
Possible resources encompass:
- Work bonuses
- Tax refunds
- Side income
- Cash gifts
- Money from selling unused objects
- Temporary reductions in discretionary spending
For instance, placing an unexpected $300 into your emergency fund may want to help you attain your first financial savings milestone faster.
Step 6: Protect Your Emergency Fund
Once you have built your financial savings, try to use the money most effectively for authentic emergencies.
Before withdrawing cash, ask yourself whether or not the expense is surprising, essential, and difficult to cover within your everyday price range.
A deliberate vacation or enjoyment buy generally belongs in a separate savings category.
Your emergency fund must be there whilst something happens which you couldn’t reasonably plan for.
Emergency Fund vs. Paying Off Debt
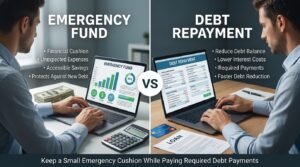
If you have debt, you may wonder whether every extra dollar needs to go toward compensation instead of savings.
There is no accepted solution.
Having a few emergency savings can provide a cushion if an unexpected expense occurs. Without any savings, you can end up using a credit card or taking on extra debt to cover the emergency.
At the same time, excessive hobby debt can end up costly if balances stay unpaid.
A practical technique can be to keep an initial emergency cushion even while making required debt payments, then decide how to divide additional cash among financial savings and debt repayment based on your circumstances.
You can also study contemporary money-management strategies through CoreFoxes.
Common Emergency Fund Mistakes
Setting an Unrealistic Goal
Trying to save a very large amount immediately can make your finances tough to manage. Start with a target that suits your income.
Using Emergency Savings for Everyday Spending
Emergency financial savings ought to no longer come to be used as a backup account for restaurants, buying, enjoyment, or other deliberate costs.
Forgetting Annual Expenses
Some expenses arise annually or at least once every year. Creating separate savings for predictable expenses can save you from the use of your emergency fund unnecessarily.
Stopping After Reaching Your First Goal
Reaching $500 or $1,000 is a vital milestone, but you could retain building your fund if your instances allow.
Failing to Rebuild After an Emergency
If you use your emergency fund, start rebuilding it once the emergency has been treated.
Final Thoughts
Building an emergency fund is a gradual process. You no longer need a large amount of cash to get started. Begin with the aid of calculating your crucial prices, select a practical savings target, automate contributions, and maintain the money reserved for real emergencies.
As your income, expenses, and financial responsibilities change, review your target and adjust your savings plan.
An emergency fund cannot prevent unexpected expenses, but it can give you more financial flexibility when they happen. Combined with a realistic monthly budget and responsible debt management, emergency savings can become an important part of a stronger personal finance plan.

