
A personal loan can help you cover a large expense, consolidate existing debt, pay for an unexpected bill, or manage another financial need. But applying for a loan without understanding the process can make it harder to compare offers and control borrowing costs.
If you are wondering how to apply for a personal loan, the process is usually easier when you prepare your finances and documents before submitting an application.
From checking your credit to comparing APRs and reviewing the final agreement, each step matters.
What Is a Personal Loan?
A personal loan is an installment loan in which a lender provides you with a specific amount of money that you repay over a set period.
Unlike a credit card, which provides revolving credit, a personal loan typically has a fixed amount and a set repayment schedule.
Personal loans can be used for various purposes, depending on the lender’s terms. Common uses include debt consolidation, major purchases, home improvements, and unexpected expenses.
Before applying, make sure you understand why you need the money and how the monthly payment will fit into your budget.
Step 1: Decide How Much You Need
The first step is determining how much you actually need to borrow.
Avoid choosing a loan amount simply because a lender says you qualify for it. Borrowing more than necessary can increase your monthly payment and total interest costs.
Start by calculating the exact expense you need to cover.
For example, if you need $7,000 for a specific expense, compare lenders based on a loan amount close to that figure instead of automatically requesting $15,000.
A smaller loan can mean lower overall borrowing costs.
Step 2: Check Your Credit
Your credit history can influence whether you qualify and what loan terms you receive.
Before applying, review your credit reports and check for errors or unfamiliar accounts. Lenders commonly use credit information when evaluating applications. A hard credit inquiry can also affect your credit score temporarily.
If your credit profile has errors, correcting them before applying may be worthwhile.
Your credit score is not the only factor lenders consider. Income, existing debt, and other financial information can also affect lending decisions.
Step 3: Calculate Your Budget
Before submitting an application, determine how much you can comfortably afford each month.
Look at your:
- Monthly income
- Rent or mortgage
- Utilities
- Existing debt payments
- Insurance
- Food and transportation
- Savings
- Other regular expenses
Then estimate how a new loan payment would fit into your budget.
A loan payment should not leave you struggling to cover essential expenses.
Step 4: Compare Different Lenders
One of the most important steps in the personal loan application process is comparing multiple lenders.
Do not automatically accept the first offer you see.
Compare:
- APR
- Interest rate
- Loan amount
- Repayment period
- Monthly payment
- Origination fees
- Late fees
- Prepayment terms
- Total repayment cost
The CFPB explains that APR includes the interest rate plus certain additional loan costs and can be useful when comparing borrowing options.
Comparing APRs instead of looking only at interest rates can give you a better picture of the overall cost.
Step 5: Check Prequalification Options
Some lenders allow potential borrowers to prequalify before submitting a full application.
Prequalification may help you understand the types of rates or loan amounts you could potentially receive.
However, prequalification does not guarantee approval.
Also check whether the lender uses a soft or hard credit inquiry during the process. A hard inquiry generally occurs when you formally apply for credit and can affect your credit score.
Step 6: Prepare Your Documents
Having your information ready can make the application process easier.
Depending on the lender, you may be asked for information such as:
- Government-issued identification
- Social Security number
- Proof of income
- Employment information
- Bank account information
- Current debts
- Monthly housing costs
Lenders can have different documentation requirements, so check their instructions before submitting your application.
Preparing documents in advance can also help prevent unnecessary delays.
Step 7: Submit the Personal Loan Application
Once you have compared lenders and selected an offer, you can submit your application.
You will typically provide personal and financial information, including details about your income, employment, housing, and existing obligations.
Make sure all information is accurate.
Providing incorrect information can cause delays or create problems during the verification process.
The lender may then review your credit history and financial information before making a decision.
Step 8: Review the Loan Offer Carefully
If your application is approved, do not rush to accept the money.
Read the loan agreement carefully.
Pay particular attention to:
APR: This helps you understand the overall borrowing cost.
Monthly payment: Make sure it fits comfortably into your budget.
Loan term: A longer term can reduce the monthly payment but may increase total interest.
Fees: Check origination, late-payment, and other applicable fees.
Prepayment terms: Check whether there are any charges for paying the loan early.
Understanding these details before accepting the loan can help you avoid surprises later.
Step 9: Accept the Loan and Receive the Funds
Once you agree to the loan terms, you can complete the final steps required by the lender.
The lender may ask you to electronically sign documents or provide additional verification.
After the loan is finalized, the funds are generally sent according to the lender’s process.
Keep copies of your loan agreement and payment information for your records.
Step 10: Start Making Payments on Time
After receiving the loan, your next priority should be making payments on time.
Set up automatic payments if that option is available and works for your budget.
Late payments can result in fees and may negatively affect your credit history.
It can also help to keep track of your remaining balance and payment schedule throughout the loan term.
Personal Loan vs Credit Card
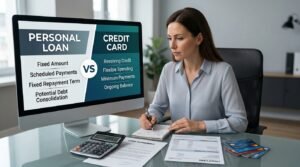
Before applying for a personal loan, consider whether it is actually the right borrowing option for your situation.
A personal loan usually provides a fixed amount with scheduled repayment, while a credit card provides revolving credit.
If you are deciding between these options, read our guide on personal loan vs credit card to compare interest rates, fees, repayment structures, and flexibility.
This comparison can be especially useful if you are considering using a personal loan to consolidate credit card debt.
Can AI Help With the Loan Process?
AI-powered personal finance tools can help you organize your budget and understand your monthly cash flow before applying for a loan.
For example, you can use AI tools to categorize expenses, identify unnecessary spending, and estimate how a new monthly payment could affect your budget.
Our guide on AI personal finance explains how AI can be used for budgeting and everyday money management.
However, AI should not replace reviewing the actual loan agreement. Always verify the lender’s APR, fees, repayment terms, and other conditions yourself.
Common Mistakes to Avoid
When applying for a personal loan, avoid these common mistakes:
- Borrowing more than you need
- Applying without checking your credit
- Comparing only monthly payments
- Ignoring APR and fees
- Accepting the first offer
- Failing to read the loan agreement
- Taking a payment you cannot comfortably afford
- Ignoring prepayment conditions
Taking time to compare offers can help you understand the actual cost of borrowing.
Final Thoughts
Learning how to apply for a personal loan does not have to be complicated.
Start by determining how much you need, check your credit, calculate your budget, compare lenders, and review APRs and fees carefully.
Once you receive an offer, read the complete agreement before accepting it. Make sure the monthly payment fits your finances and that you understand the total cost of the loan.
A personal loan can be a useful financial tool, but the right loan depends on your individual circumstances and the terms you qualify for.
FAQs
What do I need to apply for a personal loan?
Requirements vary by lender, but you may need identification, income information, employment details, banking information, and information about your existing debts.
What credit score do I need for a personal loan?
There is no single credit score requirement for every personal loan. Lenders use different eligibility criteria and may consider credit history, income, debt, and other financial information.
Does applying for a personal loan affect your credit score?
A formal loan application usually involves a hard credit inquiry, which can temporarily affect your credit score.
Should I compare multiple personal loan lenders?
Yes. Comparing multiple lenders can help you evaluate different APRs, fees, repayment terms, and monthly payments before choosing an offer.
What is more important, the interest rate or APR?
APR is useful for comparing the overall cost because it can include the interest rate and certain additional loan charges.