
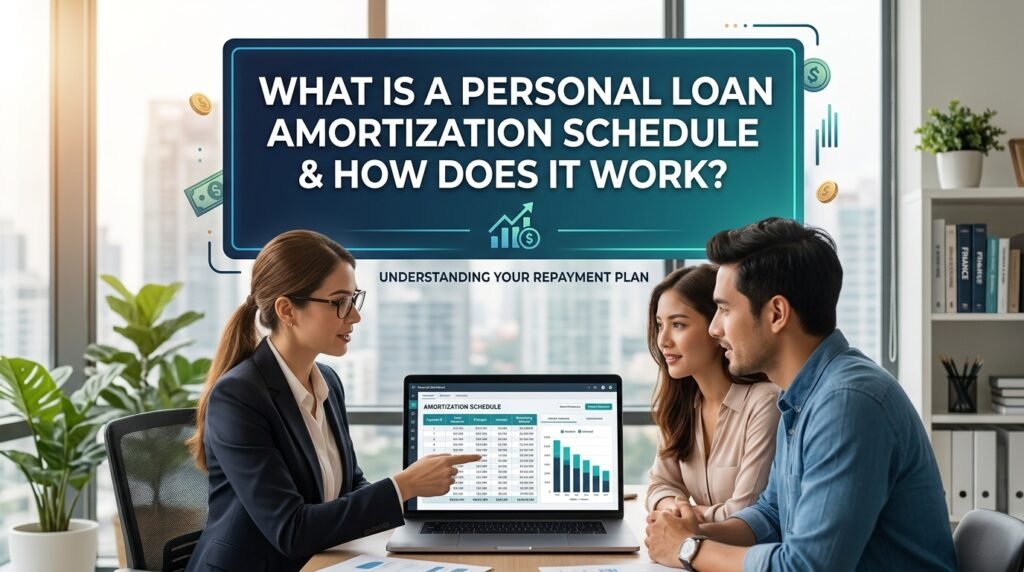
When you take out a personal loan, you usually agree to repay the borrowed amount over a specific period through regular monthly payments. But have you ever wondered how each payment is divided between principal and interest?
A personal loan amortization schedule provides a detailed breakdown of your loan payments from the beginning to the end of the repayment period. It shows how much of each payment goes toward the principal, how much goes toward interest, and how your remaining balance changes over time.
Understanding an amortization schedule can help you see the true cost of borrowing and make more informed decisions about your loan.
What Is a Personal Loan Amortization Schedule?
A personal loan amortization schedule is a table that shows how a loan is expected to be repaid over time.
For each scheduled payment, the table may show:
- Payment number
- Payment date
- Total monthly payment
- Amount applied to principal
- Amount applied to interest
- Remaining loan balance
For example, if you borrow $10,000 and agree to repay it over five years, your amortization schedule can show all 60 scheduled payments and how the balance is expected to decrease after each payment.
The exact numbers depend on factors such as your loan amount, interest rate, repayment term, and loan fees.
How Does Loan Amortization Work?
With a typical amortizing personal loan, you make regular payments throughout the repayment term.
At the beginning of the loan, a larger portion of each payment may go toward interest because interest is calculated based on the outstanding principal balance.
As you continue making payments, the principal balance decreases. As a result, the amount of interest charged over each period can also decrease.
More of your payment can then go toward reducing the principal balance.
This gradual shift is one of the key features of an amortizing loan.
Example of a Personal Loan Amortization Schedule
Consider a hypothetical personal loan of $10,000 with a fixed annual interest rate and a five-year repayment term.
Your monthly payment might remain the same throughout the loan if the loan uses a standard fixed-rate amortization structure.
However, the way that payment is divided changes over time.
For example, an early payment might look like:
- Total payment: $220
- Interest: $80
- Principal: $140
- Remaining balance: reduced by $140
Later in the loan, the payment might still be $220, but the allocation could look more like:
- Total payment: $220
- Interest: $30
- Principal: $190
- Remaining balance: reduced by $190
These numbers are only illustrative. Actual payments and allocations depend on the loan’s terms.
Principal vs. Interest
Understanding principal and interest is essential when reading an amortization schedule.
Principal
The principal is the amount you originally borrow. When part of your monthly payment is applied to principal, your outstanding loan balance decreases.
For example, if you owe $8,000 and $150 of your payment goes toward principal, your new principal balance would be approximately $7,850, assuming no other charges or adjustments.
Interest
Interest is the cost charged by the lender for providing the money.
Interest is generally calculated based on the outstanding balance and the applicable interest rate. As the principal balance decreases, the interest portion of future payments may also decrease.
This is why two payments with the same total amount can have different principal and interest allocations.
Why Is an Amortization Schedule Important?
An amortization schedule gives you a clearer picture of how your loan works.
Instead of looking only at the monthly payment, you can see how much you are paying toward the actual loan balance and how much is going toward interest.
This can help you understand:
- How quickly your balance is declining
- How much interest you may pay over the loan term
- When most of your principal will be repaid
- How additional payments could affect the balance
- How the repayment term affects total borrowing costs
For a broader look at the costs involved in borrowing, you can read How to Calculate the True Cost of a Personal Loan Before You Sign.
How Does the Loan Term Affect Amortization?
The repayment term can have a significant effect on your amortization schedule.
A shorter loan term generally means you repay the principal faster. However, your required monthly payment may be higher because you have fewer payments to make.
A longer repayment term can result in a lower required monthly payment because the balance is spread over more months. However, you may pay more interest over the life of the loan.
For example, a $10,000 loan could have different monthly payments and total interest costs depending on whether it is repaid over three years, five years, or another period.
This is why borrowers should consider both monthly affordability and total repayment cost.
How Does the Interest Rate Affect an Amortization Schedule?
The interest rate also influences how much of each payment goes toward interest.
Suppose two borrowers take out the same loan amount for the same repayment period. If one borrower receives a lower interest rate, that borrower may have a lower monthly payment and lower total interest costs, assuming other loan terms are the same.
A higher interest rate can increase the interest portion of payments and the overall cost of borrowing.
When comparing loan offers, do not look only at the advertised monthly payment. Review the interest rate, APR, fees, loan term, and total repayment amount.
How Are Personal Loan Monthly Payments Calculated?
A typical fixed-rate personal loan payment is calculated using the loan amount, interest rate, and repayment term.
The calculation determines a payment amount designed to repay the loan over the agreed term.
Your monthly payment can then be divided between principal and interest according to the loan’s amortization structure.
If you want to understand the calculation in more detail, see What Is a Personal Loan Monthly Payment and How Is It Calculated?.
The monthly payment shown in a loan agreement may not tell you the complete story. A loan with a lower monthly payment could have a longer term and potentially result in higher total interest.
Can Extra Payments Change an Amortization Schedule?
Making additional payments toward your principal may reduce the outstanding balance faster, depending on your lender’s terms.
For example, if your required monthly payment is $300 and you pay an additional $50 toward principal, the balance may decline faster than it would under the original payment schedule.
Reducing the principal sooner can potentially reduce future interest because interest is generally calculated based on the outstanding balance.
However, borrowers should check whether their loan has any prepayment restrictions, penalties, or specific instructions for applying extra payments.
You can also learn more about strategies for reducing loan costs in How to Pay Off a Personal Loan Faster and Save on Interest.
What Information Should You Look for on an Amortization Schedule?
When reviewing an amortization schedule, pay attention to several important details.
Payment Number
This identifies the payment in the repayment sequence, such as payment 1, payment 2, and so on.
Payment Amount
This shows the amount scheduled for each payment. For a fixed-rate loan, the principal and interest payment may remain consistent, although other charges could affect the amount you actually owe.
Principal Portion
This shows how much of the payment reduces your outstanding loan balance.
Interest Portion
This shows how much of the payment represents interest charged for that period.
Remaining Balance
This shows how much principal remains after the payment is applied.
Together, these figures help you track how the loan progresses from the original balance toward a zero balance.
Is an Amortization Schedule the Same as a Loan Statement?
Not necessarily.
An amortization schedule is generally a planned repayment table showing how payments are expected to be allocated throughout the loan term.
A loan statement provides information about your actual account activity, which may include payments received, fees, interest charged, adjustments, and your current balance.
If you make extra payments or if your account experiences changes that affect repayment, the actual loan balance may differ from the original projected amortization schedule.
Final Thoughts
A personal loan amortization schedule provides a useful view of how your loan is expected to be repaid over time. It shows how each payment is divided between principal and interest and how your outstanding balance gradually decreases.
The loan amount, interest rate, and repayment term all influence the schedule and the total cost of borrowing.
Before taking out a personal loan, review the payment amount and total repayment cost rather than focusing only on whether the monthly payment fits your budget. Understanding the amortization schedule can help you see where your money is going and how quickly you are building toward paying off the loan.
Frequently Asked Questions
What is a personal loan amortization schedule?
A personal loan amortization schedule is a table showing scheduled loan payments, including the principal and interest portions of each payment and the remaining loan balance.
Does the monthly payment stay the same throughout an amortized loan?
For many fixed-rate amortizing personal loans, the scheduled principal and interest payment remains the same. However, the amount allocated to principal and interest changes over time.
Does more of the payment go toward interest at the beginning?
Generally, yes. Because the outstanding principal balance is higher at the beginning, the interest portion can represent a larger part of the payment.
Can extra payments reduce total interest?
Additional principal payments may reduce the outstanding balance faster, which can potentially reduce future interest. Check your lender’s terms before making extra payments.
Does a longer loan term increase total interest?
A longer repayment term can reduce the required monthly payment, but it may result in more total interest paid because the loan remains outstanding for a longer period.
Where can I find my personal loan amortization schedule?
Your lender may provide an amortization schedule with your loan documents or make it available through your online account. You can also request one directly from the lender.

