
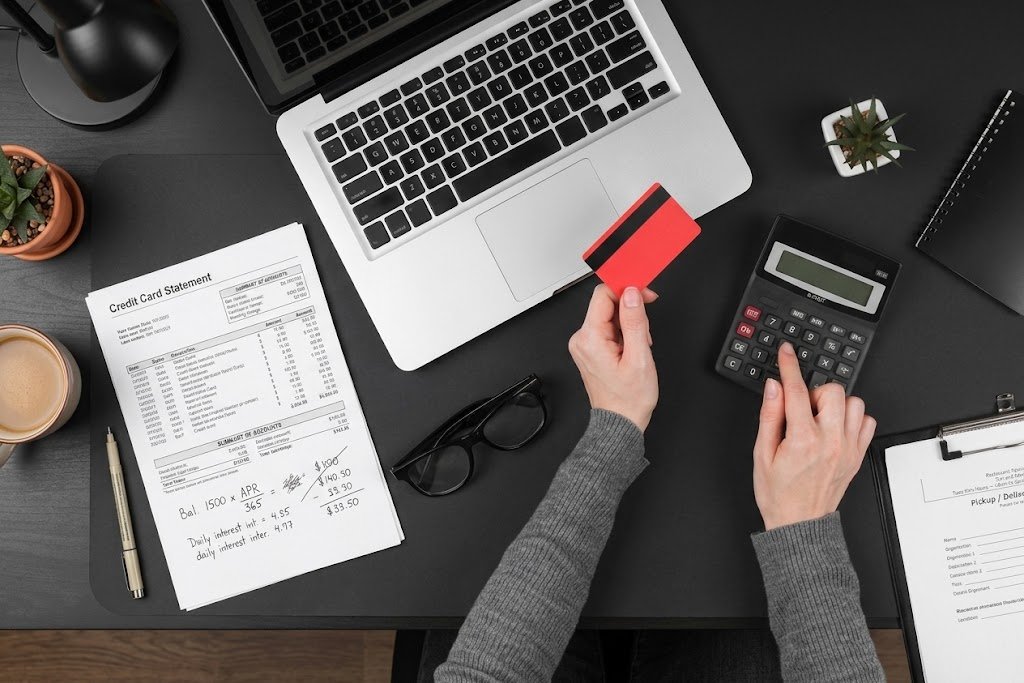
Credit card interest calculation is one of those things almost everyone assumes they understand — until they actually try to work out what a “small” leftover balance is really costing them. The advertised APR looks simple enough on a statement, but the way that number turns into an actual dollar charge involves a few steps most cardholders have never walked through.
That gap in understanding is exactly why carrying even a modest balance month to month tends to cost far more than intuition suggests.
How Credit Card Interest Calculation Actually Works
The APR printed on a credit card statement is an annual figure, but interest doesn’t get applied once a year — it accrues daily. Most issuers use a method called the average daily balance, which involves a specific sequence most people never see broken down.
First, the issuer converts the APR into a daily periodic rate by dividing it by 365. A 24% APR, for example, becomes roughly a 0.066% daily rate. Next, the issuer tracks the balance owed on the card for every single day in the billing cycle and averages those daily balances together. Finally, that average is multiplied by the daily rate, then by the number of days in the cycle, to produce the interest charge.
According to the Consumer Financial Protection Bureau, this daily compounding is exactly why paying even a few days late, or carrying a balance for only part of a cycle, still generates a real charge — the calculation doesn’t wait for a full month to start counting.
Why Small Balances Cost More Than the Math Suggests
The instinct that a small balance means small interest isn’t wrong, exactly — it’s just missing a second layer most people don’t account for.
Interest compounds on unpaid interest. If a balance isn’t paid in full, next month’s interest is calculated on a balance that already includes last month’s interest charge. Over several cycles, that compounding effect grows faster than a flat percentage suggests.
Grace periods disappear once a balance is carried. Most cards offer a grace period — no interest charged if the statement balance is paid in full by the due date. But according to Experian, carrying even a small unpaid balance from the previous cycle typically means new purchases start accruing interest immediately, with no grace period at all, until the full balance is cleared again.
A “small” balance is relative to the APR, not the dollar amount. A $50 balance on a card with a 29% APR behaves very differently over a year than the same $50 on a 15% APR card. Because average credit card APRs have climbed in recent years, the cost of carrying almost any balance has quietly gotten steeper than it may have been a few years ago.
Minimum payments are structured to extend the timeline. Minimum payments are typically calculated as a small percentage of the balance, which means a large share of each minimum payment goes toward interest rather than principal — especially early on, when the balance is still relatively high.
How to Actually See What a Balance Is Costing You
Understanding credit card interest calculation in the abstract is less useful than seeing it applied to a real balance.
- Find the daily periodic rate by dividing the card’s APR by 365.
- Check the average daily balance on the most recent statement — most issuers now disclose this directly rather than requiring you to calculate it.
- Multiply the average balance by the daily rate, then by the days in the cycle, to see the actual interest charge behind the number on the bill.
- Compare that charge to what a full payoff would have cost — zero, thanks to the grace period — to see the real price of carrying the balance forward.
- Use a payoff calculator for multi-month balances, since manual calculation gets complicated once compounding and new purchases are involved.
This kind of exact, unemotional look at the numbers pairs well with automating your finances — once the real cost of carrying a balance is visible, setting up a full-balance autopay stops feeling optional and starts feeling obvious.
Why This Is Easy to Underestimate
Most people don’t do credit card interest calculation by hand — they just glance at the minimum due and pay something close to it, assuming a small gap between the minimum and the full balance is a minor difference. It rarely is. The same instinct that treats a small purchase as harmless because of The Latte Factor Myth tends to show up here too — a small number feels insignificant in isolation, even when the underlying math compounds it into something much larger.
For some people, the discomfort of doing this calculation honestly connects back to deeper money scripts around avoidance — it’s easier not to look closely at a balance than to confront what it’s actually costing every month.
Final Thoughts
Credit card interest calculation isn’t complicated once it’s broken down, but almost no one sees it broken down, which is exactly why “just a small balance” so often costs more than expected. The daily compounding, the lost grace period, and the structure of minimum payments all work quietly in the same direction.
The fix isn’t complicated either: pay the statement balance in full whenever possible, and if a balance has to be carried, know the real daily math behind it rather than trusting the sticker-shock-free feeling of a low minimum payment.

