Credit Card Balance Transfer Fees Explained: The Math Most People Get Wrong
A 0% APR balance transfer offer sounds like free money. Move your high-interest debt to a new card, pay nothing in interest for over a year, and walk away having saved hundreds of dollars. That’s the pitch, and it’s often true. But balance transfer fees are the part of that pitch that gets glossed over, and getting the math wrong here is one of the most common ways people end up saving far less than they expected, or in some cases, losing money on a transfer they thought was a slam dunk.
Balance transfer fees typically run 3% to 5% of whatever amount you move, charged upfront regardless of how much interest you end up avoiding. That single detail changes the math on a lot of “0% APR” offers more than people expect. Let’s break down exactly how balance transfer fees work, when they’re worth paying, and where the math quietly falls apart.
What Are Balance Transfer Fees?
A balance transfer fee is a one-time charge, imposed by the new card issuer, for moving an existing balance from one credit card to another. It’s separate from interest, separate from any annual fee, and it’s charged whether or not you end up saving money on interest overall.
Most issuers charge between 3% and 5% of the transferred amount as their balance transfer fee, usually with a minimum flat fee, often $5 to $10, if that percentage comes out to a small number. So on a $5,000 transfer at a 3% rate, you’d pay $150 upfront in balance transfer fees, added directly to your new card’s balance before you’ve made a single payment.
This is the reason a “0% APR” balance transfer offer isn’t actually free. You’re not paying interest during the promotional period, but you are paying a balance transfer fee for the privilege of moving the debt in the first place.
Why Issuers Charge a Transfer Fee
Card issuers charge this balance transfer fee partly to cover the administrative cost of paying off your old account, and partly because balance transfers are genuinely valuable to consumers, which means issuers can charge for the service and still attract customers. Some issuers waive their balance transfer fee entirely as a promotional perk, particularly for well-qualified applicants, but a true no-fee balance transfer is the exception rather than the norm.
The Balance Transfer Math Most People Get Wrong
Here’s where the confusion usually happens. People compare the 0% promotional APR to their current card’s interest rate and assume the difference is pure savings. It isn’t, because balance transfer fees have to be subtracted from that savings before you know your actual gain.
According to Federal Reserve consumer credit data, average credit card interest rates on accounts that carry a balance have remained in the high-teens to low-20% range through 2026. That’s the rate you’re comparing your balance transfer fee against, and it’s a big enough number that paying the fee usually does make sense. But “usually” isn’t “always,” and the math depends heavily on your specific balance, fee, and payoff timeline.
A Real Example With the Numbers
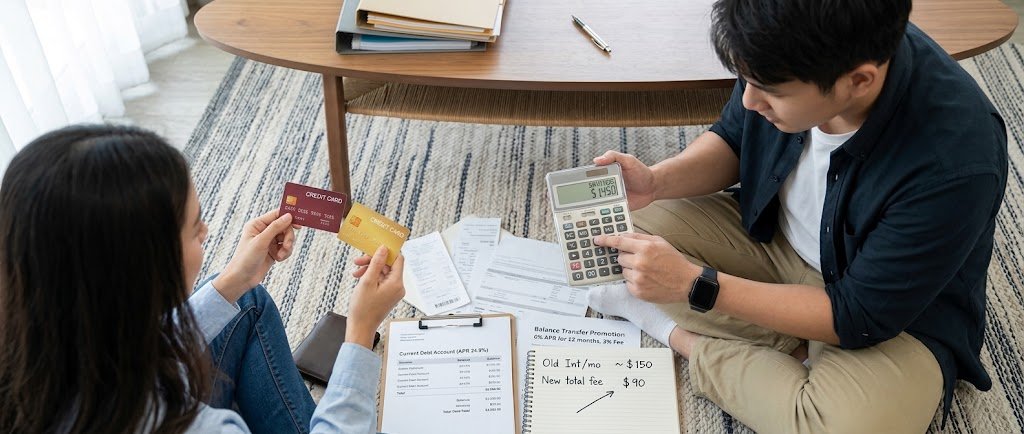
Say you have a $4,000 balance sitting on a card charging 22% APR. You’re offered a new card with a 0% intro APR for 15 months and a 3% balance transfer fee.
The balance transfer fee: 3% of $4,000 is $120, charged upfront.
What you’d pay in interest if you didn’t transfer: If you paid that $4,000 down over 15 months at 22% APR, you’d pay roughly $650 to $700 in interest, depending on exactly how you structured payments.
What you actually pay after transferring: Just the $120 balance transfer fee, assuming you pay off the full balance before the promotional period ends.
Net savings: Roughly $530 to $580, even after subtracting the balance transfer fee.
This is a hypothetical example meant to illustrate the math, not an exact calculation for any specific card or balance. Your own numbers will depend on your interest rate, balance, and how quickly you pay it down. For a more precise picture, running your own balance transfer fee math through a credit card interest calculation tool before transferring is worth the ten minutes it takes.
When the Transfer Fee Outweighs the Savings
The example above works because the balance was large enough that the interest savings clearly outweighed the balance transfer fee. That’s not always the case.
Small balances. On a $500 balance, a 3% balance transfer fee is $15. If you were already planning to pay that off within a month or two anyway, the interest you’d save might not even cover it.
Short promotional periods paired with slow payoff plans. If your promotional period is 6 months but your realistic payoff timeline is 18 months, you’ll be paying the card’s regular ongoing APR for a full year after the promotion ends, on top of the balance transfer fee you already paid.
Repeated transfers. Moving the same debt from card to card every time a promotional period ends, sometimes called “credit card churning” for debt, means paying a new balance transfer fee every single time, which can quietly erode most of the benefit over several rounds.
High-fee, short-promotion offers. Occasionally a card advertises a 0% APR for a very short window (3 to 6 months) paired with a 5% balance transfer fee. On a large balance, that fee alone can outweigh what you’d realistically save in that short a timeframe.
How to Calculate If a Balance Transfer Is Worth It
Step 1: Add Up the Fee
Multiply your balance by the balance transfer fee percentage. A $6,000 balance at a 4% fee is $240. Know this number before anything else.
Step 2: Estimate Your Current Interest Cost
Look at your current card’s APR and estimate how much interest you’d pay over the time it would realistically take you to pay off the balance. Your monthly statement usually shows this, or you can estimate it using your card’s disclosed APR and balance. The Consumer Financial Protection Bureau’s credit card comparison tools can help you understand how your current card’s terms compare to what’s being offered, including any balance transfer fee attached to a new card.
Step 3: Compare the Two Numbers
If the interest you’d avoid is meaningfully larger than the balance transfer fee, the math favors transferring. If the numbers are close, the fee alone may make the transfer not worth the hassle, the temporary dip from a new credit inquiry, or the risk of missing the promotional deadline.
Step 4: Plan Your Payoff Before You Transfer
A balance transfer only pays off if you actually pay down the balance during the promotional window. Before transferring, map out a debt-free journey with a specific monthly payment amount that will clear the balance before the promotional APR expires. Without that plan, balance transfer fees become just another cost added to debt that keeps rolling over.
Common Mistakes With Balance Transfers
Ignoring the fee entirely. The most common mistake is comparing only the interest rates and forgetting the balance transfer fee is a real, immediate cost that reduces your savings from day one.
Not checking whether new purchases get the same rate. Some cards apply the 0% rate only to the transferred balance, not to new purchases made on the card, which can result in unexpected interest charges that stack on top of the balance transfer fee you already paid. Reading how to read your credit card statement carefully after a transfer helps catch this early.
Missing the promotional deadline. If you haven’t paid off the transferred balance before the promotional period ends, the remaining amount typically jumps to the card’s standard ongoing APR, which can be significantly higher than what you started with, on top of the balance transfer fee already spent getting there.
Applying for a card without checking the fee upfront. Balance transfer fees are usually disclosed in the card’s terms before you apply. Comparing offers side by side, including each card’s specific balance transfer fee, before applying rather than after approval avoids unpleasant surprises.
Not considering whether negotiating your current rate is simpler. Sometimes it’s worth trying to negotiate your credit card interest rate directly with your current issuer before going through the balance transfer process and its fee, especially if your balance is small enough that the math doesn’t clearly favor a transfer.
Practical Takeaways
- Balance transfer fees typically run 3% to 5% of the amount transferred and are charged regardless of how much you save on interest.
- Always subtract the balance transfer fee from your estimated interest savings before assuming a transfer is worth it.
- Transfers tend to make the most sense on larger balances with a clear, realistic payoff plan within the promotional window, since that’s when the balance transfer fee is easiest to outweigh.
- Small balances, short promotional periods, or repeated transfers can erode or eliminate the benefit once the balance transfer fee is factored in.
- A balance transfer fee only pays for itself if you actually pay down the balance, not if it becomes a place to park debt indefinitely.
Final Thoughts
Balance transfer fees aren’t a reason to avoid balance transfers altogether. In most cases, especially on larger balances carried at high interest rates, the math still favors transferring even after accounting for the fee. But treating a 0% APR offer as automatically free money, without running the actual numbers on the balance transfer fee, is how the math quietly works against you instead of for you.
Before you transfer anything, do the two-minute calculation: multiply your balance by the balance transfer fee percentage, estimate your realistic interest savings, and compare the two. If the savings clearly outweigh the fee and you have a solid plan to pay off the balance in time, a balance transfer can be one of the more effective tools for getting out of high-interest debt faster.
This article is for general educational purposes and isn’t personalized financial advice. Card terms, balance transfer fees, and promotional rates vary by issuer and change over time, so review your specific card’s disclosures and consider your own financial situation before transferring a balance.