
Financial Literacy for Teens: Money Lessons Schools Don’t Teach
Most adults remember the first paycheck that came in smaller than expected, and the confusion that followed. Nobody had explained withholding, and nobody had mentioned that a “$15 an hour” job doesn’t mean $15 in your hand. Financial literacy for teens exists to remove that kind of surprise before it happens, ideally while the stakes are still low.
This guide covers what schools tend to cover, what they often leave out, and the practical skills worth learning before 18. You’ll also find a realistic example, a few common mistakes, and takeaways you can act on this week.
Why Financial Literacy for Teens Matters Now
Teenagers today handle money in ways their parents never did. Tap-to-pay, peer-to-peer apps, buy-now-pay-later offers and in-app purchases make spending nearly frictionless. Cash at least feels like it’s leaving your hand. A phone screen doesn’t.
At the same time, the stakes of getting started late keep rising. Young adults face credit decisions, student loan choices and housing costs soon after graduation, often with no practice run.
Schools are catching up. The Council for Economic Education’s 2026 Survey of the States found that 39 states now require personal finance courses for high school graduation, and California, Delaware, Colorado and Hawaii newly mandated a semester-long course. You can read the full findings in the Council for Economic Education’s Survey of the States announcement.
That is real progress, but a requirement on paper doesn’t guarantee a strong lesson in the classroom.
What School Classes Cover, and What Gets Left Out
Even in states with a requirement, the quality of financial literacy for teens varies widely. Reporting on the survey notes that 13 of the 39 states allow personal finance to be woven into other courses rather than taught as its own class. A unit squeezed into an economics course can easily be reduced to a week of vocabulary.
Typical classroom coverage includes checking accounts, basic budgeting and a first look at credit. What often gets thin treatment is the practical, messy side:
- How a paycheck actually shrinks after withholding
- What a credit card statement really tells you
- How interest compounds against you on debt and for you on savings
- How to spot a scam or a too-good-to-be-true offer
- How to say “I can’t afford that” to friends without embarrassment
Research suggests the effort is worth it. A Federal Reserve Bank of New York study cited by the Council found that people who received mandatory financial education in high school were more likely to make sound financial decisions as adults. The takeaway is that early teen money education tends to pay off, and it works best when families reinforce it at home.
Teen Money Skills Worth Learning Before 18
Strong financial literacy for teens comes down to a handful of habits, each of which can be practiced with small amounts of real money.
Budgeting with real income. A budget is easier to understand when the money is yours. Whether it comes from allowance, a part-time job or birthday gifts, a simple split works well: some for spending, some for saving, some for a goal. Teens who like a tangible system may enjoy the envelope budgeting method, which makes limits visible in a way an app balance doesn’t.
Pausing before buying. Impulse spending is the first money habit that most teens (and adults) need to manage. Try a cooling-off period before any non-essential purchase. The 24-hour rule for spending is a simple version: wait a day, then decide whether you still want it.
Understanding how interest works. Interest is the single most important concept schools tend to rush. When you save, interest works for you. When you borrow, it works against you. A teen who understands how credit card interest is calculated is far less likely to carry a balance carelessly later on.
Saving with a purpose. Saving “whatever is left” rarely works, because there usually isn’t any left. Saving toward a named goal, such as a car repair fund, a laptop or first-month rent, is more motivating. Where the money sits also matters, and it helps to understand the difference between high-yield and regular savings accounts before opening a first account.
Learning how credit gets built. Credit is the area where financial literacy for teens most often falls short in class, and it feels abstract until a teen needs an apartment or a car loan. Most teens can’t open a credit card on their own, but they can learn the mechanics early. Our guide to building credit from scratch explains the starting points, and it’s worth reviewing the difference between an authorized user and a joint account holder before a parent adds a teen to any account. The two roles carry very different responsibilities.
Investing basics and time. This part of teen money education is about concepts, not big numbers. Money invested early has more time to grow, and growth is never guaranteed. A starter guide on investing for beginners with $50 a month can make the idea concrete without overpromising.
If a teen has earned income, retirement accounts enter the picture too. The IRS announced that the 2026 IRA contribution limit rises to $7,500, and IRA contributions generally can’t exceed what a person actually earned that year. For a minor, an adult typically opens and manages a custodial account. Whether that makes sense depends on the family’s situation, so it’s a good topic for a conversation with a qualified tax professional.
Earning, taxes and side income. Many teens first meet taxes through a pay stub, and learning to read one is a practical piece of financial literacy for teens. Walking through the lines (gross pay, federal withholding, Social Security and Medicare) turns a confusing document into a real lesson. Teens who want to earn more can explore side hustles that actually pay, keeping in mind that self-employment income may have its own tax rules.
A Hypothetical Example: Maya’s First Summer Job
Here is an illustration, not a real case or a recommendation. Suppose Maya, 16, works a summer job and earns $1,800 before taxes. Her first paycheck is smaller than expected because of payroll withholding, which is the surprise mentioned earlier.
Instead of treating the shortfall as a mystery, Maya and a parent go through the pay stub line by line. Then she splits what she takes home into three parts: spending money for the summer, savings toward a used laptop, and a small amount set aside for longer-term goals. She also uses a 24-hour wait on any purchase over $30.
By the end of the summer, she hasn’t become a financial expert. But she has practiced budgeting, delayed gratification and reading a pay stub, which are the core of financial literacy for teens. Those money skills carry over to her first apartment, first car loan and first real budget.
How Parents Can Support Financial Literacy for Teens
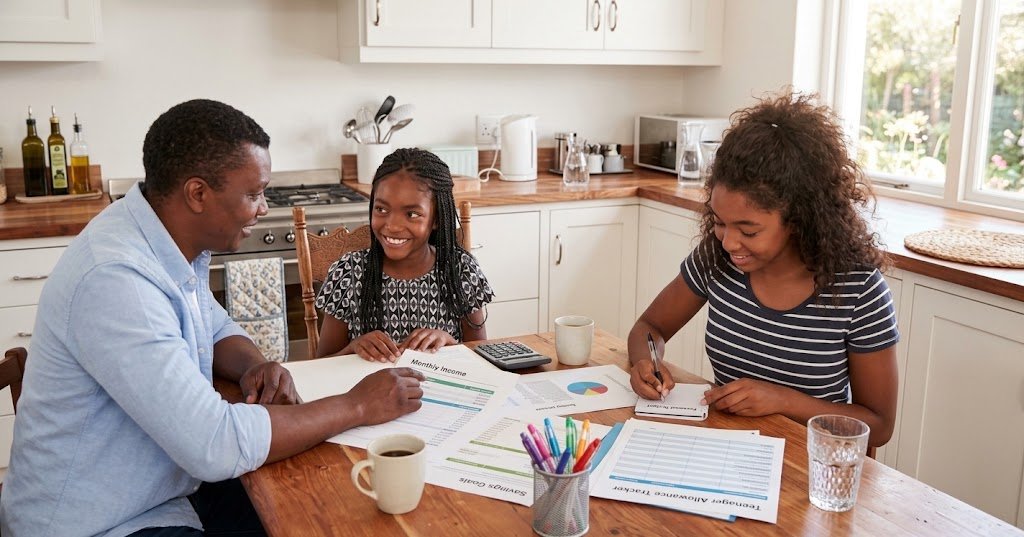
Classroom lessons stick better when they connect to daily life. A few low-pressure ways parents and guardians can help:
- Talk about money openly. Explain why you chose one grocery brand, how you compare prices or why you’re saving for a repair. Teens learn from watching.
- Let small mistakes happen. A teen who overspends $20 and has to go without for a week learns more than one who is rescued. Low-cost mistakes are cheap tuition.
- Hand over a real account. A teen checking or savings account, opened with an adult as joint owner or custodian, lets them practice with real balances and real fees.
- Review statements together. Looking at a bank or card statement with a teen is excellent practice for spotting errors and unfamiliar charges.
- Set goals together. Ask what they want to buy or do in the next year, then work backward to a weekly savings amount.
The goal isn’t to control a teen’s spending. It’s to give them room to practice decisions while a safety net still exists.
Common Mistakes Teens (and Parents) Make
Even well-meaning families stumble. Watch for these:
- Treating financial literacy for teens as a one-time talk. One big lecture rarely sticks. Short, regular conversations work better than a single sit-down.
- Teaching only saving, never spending. Teens also need to learn that spending on things you value is fine. Budgets fail when they feel like punishment.
- Ignoring digital payments. Apps and in-game purchases are where many teens first lose track of money, so include them in every conversation about teen money management.
- Skipping the credit conversation. Many young adults hit their first credit decision unprepared. Starting early removes the mystery.
- Chasing “get rich” content. Social media is full of promises of fast returns. Teens benefit from learning that real investing is slow, uncertain and boring, and that anything promising guaranteed returns deserves suspicion.
Practical Takeaways
- Start with small amounts of real money, because practice beats theory.
- Use a simple budget split, with a share each for spending, saving and a specific goal.
- Add a 24-hour pause before non-essential purchases.
- Learn how interest works on both savings and debt before borrowing.
- Read a real pay stub together at least once.
- Explore credit-building basics before a teen needs credit, and understand the responsibilities of any shared account.
- Treat financial literacy for teens as an ongoing conversation, not a single lesson.
Final Thoughts on Financial Literacy for Teens
Schools are making progress, and more states now require some form of personal finance instruction. But a required class is a starting point, not a finish line. The habits that matter most (pausing before purchases, understanding interest, saving toward goals and reading the fine print) are built through repeated practice at home, with real money and real consequences small enough to learn from.
Teens who build these skills early don’t just avoid costly mistakes. They gain confidence, and confidence makes every later money decision a little easier. Whether you’re a teen reading this yourself or a parent helping one, start small, stay curious and keep the conversation going.
Disclaimer: This article is for general educational purposes only and is not personalized financial, tax or legal advice. Rules, limits and account options change, so consider consulting a qualified professional about your specific situation.

