aiman

Person reviewing loan paperwork and a credit line statement side by side at a desk

Personal Line of Credit vs Personal Loan: What’s the Real Difference?

Understanding a personal loan vs line of credit starts with one core question: do you need a fixed amount of money all at once, or flexible access to funds over time? If you’ve seen both terms used interchangeably online, they’re actually not the same thing, and mixing them up can cost you more in interest

Personal Line of Credit vs Personal Loan: What’s the Real Difference? Read More »
Person calculating loan payments while comparing paperwork for different loan term lengths

Loan Term Length Explained: Why a Longer Loan Isn’t Always the Cheaper Option

Loan term length is one of the most important factors to consider when borrowing money. It determines how long you will make payments and has a direct effect on both your monthly payment and total interest cost. A longer loan term can make monthly payments more affordable, but it can also increase the amount you

Loan Term Length Explained: Why a Longer Loan Isn’t Always the Cheaper Option Read More »

Person comparing payday loans vs personal loans and calculating repayment costs

Payday Loans vs Personal Loans: Why One Can Trap You in a Debt Cycle

Payday vs Personal Loans: Understanding the Difference When money is tight before payday, understanding payday vs personal loans can help you choose a borrowing option based on its cost, repayment schedule, and potential risks. Both types of loans can provide access to cash quickly, and both may be available to borrowers who do not have

Payday Loans vs Personal Loans: Why One Can Trap You in a Debt Cycle Read More »

Person using a magnifying glass to read the fine print on a 0% APR credit card offer

0% APR Credit Cards: The Catch Most People Don’t Read in the Fine Print

The 0% APR catch is hiding in almost every “no interest” offer you’ve ever seen advertised — and most people don’t find out about it until the bill arrives. The headline number looks simple: 0% interest for 12, 15, or even 21 months. But the terms behind that offer decide whether it actually saves you

0% APR Credit Cards: The Catch Most People Don’t Read in the Fine Print Read More »

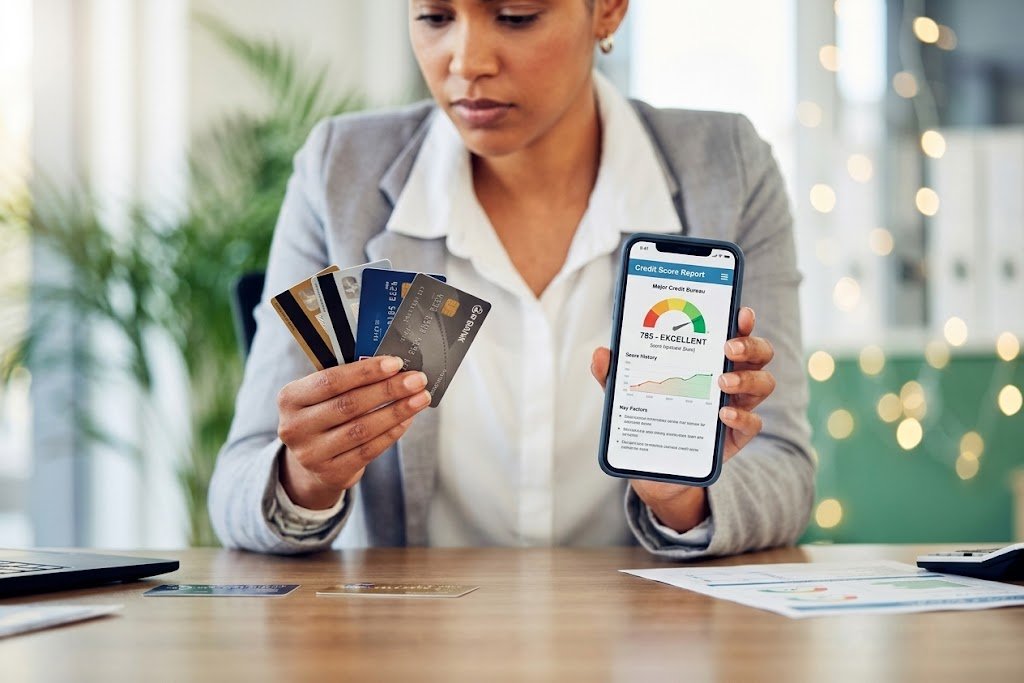
Person comparing one card vs multiple cards while checking their credit score on a smartphone

Multiple Credit Cards vs One Card: What’s Actually Better for Your Credit Score?

Choosing between one card vs multiple cards is a question almost everyone with credit eventually asks, and the honest answer depends on how you use the cards, not just how many you have. It’s not really about a magic number. It’s about how each choice interacts with the specific factors that make up your score

Multiple Credit Cards vs One Card: What’s Actually Better for Your Credit Score? Read More »

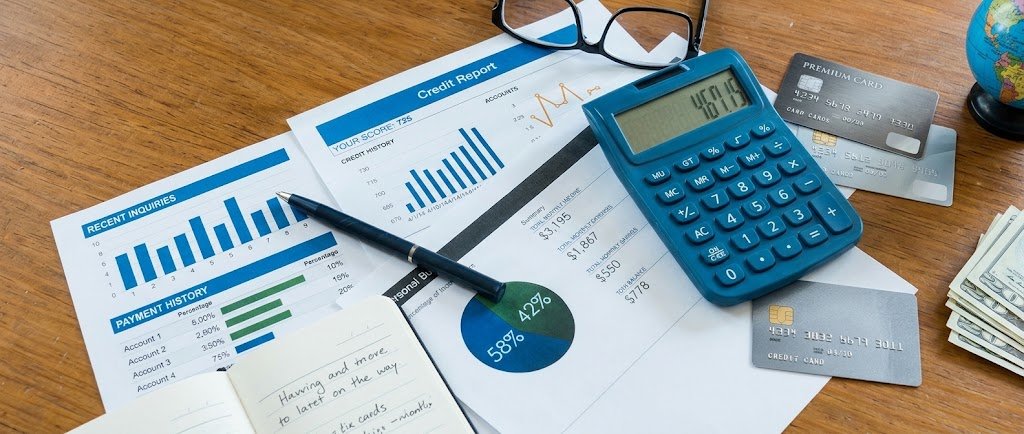
Credit card and calculator on a desk illustrating a credit card limit increase and its effect on a credit score

Credit Card Limit Increase: Does Requesting One Hurt or Help Your Score?

A credit card limit increase can help your credit score, hurt it slightly, or leave it unchanged. The outcome depends on two things: how your issuer checks your credit when you ask, and what you do with the extra credit once you have it. Here’s the short version: Hard inquiry: may cause a small, temporary

Credit Card Limit Increase: Does Requesting One Hurt or Help Your Score? Read More »

Phone screen showing scheduled savings transfers, a simple step in automating your finances

Automating Your Finances: How to Save Money Without Relying on Willpower

Automating your finances means setting your money up to move on its own, so saving, bill payments, and investing happen without you having to remember or decide each time. That matters because good intentions are unreliable. Some months you feel motivated. Other months a rough week, an appealing sale, or a forgotten due date gets

Automating Your Finances: How to Save Money Without Relying on Willpower Read More »

Piggy bank beside a 30-day calendar for a no-spend month challenge

No-Spend Month Challenge: What Really Happens When You Stop Spending for 30 Days

A no-spend month challenge is a 30-day reset where you spend money only on true essentials and pause everything else. It sounds simple. The harder question is what it actually does to your budget, and whether the savings are worth the effort. This guide answers that with real numbers instead of dramatic before-and-after stories. You’ll

No-Spend Month Challenge: What Really Happens When You Stop Spending for 30 Days Read More »

Calculator and notebook used to work out a financial independence number for retirement

Financial Independence Number: How Much Money Do You Actually Need to Retire?

Your financial independence number is the amount of invested money that can cover your living costs so that working becomes optional. It’s often shortened to your FI number. Most retirement advice gives you a single figure, usually $1 million, and stops there. That figure means very little until you know what you actually spend. Your

Financial Independence Number: How Much Money Do You Actually Need to Retire? Read More »

Person pausing before completing an online purchase, illustrating the 24-hour rule for spending

The 24-Hour Rule: A Simple Trick That Stops Impulse Spending Before It Starts

You’re scrolling, you see something, and before you’ve really thought about it, it’s in your cart and the order is placed. The 24-hour rule for spending is a simple behavioral trick designed to interrupt that exact moment — not by banning purchases, but by forcing a delay long enough for the impulse to fade before

The 24-Hour Rule: A Simple Trick That Stops Impulse Spending Before It Starts Read More »