
You check your credit card account after making a purchase and notice that the transaction says “pending” instead of showing as a completed charge. You may wonder whether the money has already been charged, whether your available credit is affected, or why the transaction has not posted yet.
A pending credit card transaction is generally a purchase or authorization that has been approved but has not yet fully processed as a final posted transaction.
Pending transactions are common with everyday purchases, online shopping, restaurants, hotels, gas stations, and other merchants. Understanding how they work can help you avoid confusion about your credit card balance and available credit.
What Is a Pending Credit Card Transaction?
A pending credit card transaction is a transaction that has been authorized but has not yet been finalized by the merchant and card issuer.
When you use your credit card, the merchant usually sends an authorization request to your card issuer. The issuer checks whether enough available credit exists and may approve the transaction.
The transaction can then appear as pending in your credit card account.
For example, suppose you have a $5,000 credit limit and make a $200 purchase. The transaction may immediately appear as pending even though it has not yet become a posted charge.
The exact way the transaction appears can vary between credit card issuers.
Does a Pending Transaction Reduce Available Credit?
Yes, a pending transaction can reduce your available credit even before the charge officially posts.
For example, imagine you have:
- Credit limit: $5,000
- Existing balance: $1,500
- Available credit: $3,500
- Pending transaction: $400
The pending $400 transaction may temporarily reduce your available credit to approximately $3,100.
This does not necessarily mean that the $400 has already become part of your final posted balance.
The issuer may reserve that amount while waiting for the merchant to complete the transaction.
Is a Pending Transaction the Same as a Posted Charge?
No.
A pending transaction and a posted charge are different stages of the payment process.
A pending transaction has generally been authorized but has not yet been finalized.
A posted transaction has completed processing and becomes part of your account’s finalized activity.
For example, you might purchase something online for $150. The transaction may first appear as pending and later change to a posted charge.
Once it posts, the transaction becomes part of your finalized account activity.
This distinction is important because your available credit and account balance may not always change in exactly the same way at the same time.
Why Do Credit Card Transactions Stay Pending?
There are several reasons why a transaction may remain pending.
One common reason is that the merchant has not yet completed the transaction.
Some businesses process transactions in batches rather than immediately. The transaction may therefore remain pending until the merchant submits the final charge.
The timing can also depend on the merchant, payment network, card issuer, weekends, holidays, or the type of purchase.
Online purchases may remain pending while the merchant prepares or ships the order.
Hotels and rental car companies may also use temporary authorizations because the final amount may not be known when the transaction begins.
How Long Does a Pending Credit Card Transaction Take?
There is no single processing time that applies to every transaction.
Some pending transactions may post relatively quickly, while others can remain pending for several days.
The timing depends on factors such as:
- Merchant processing practices
- Type of transaction
- Card issuer
- Payment network
- Weekends and holidays
- Whether the merchant has finalized the transaction
A temporary authorization can sometimes remain visible until it is replaced by a final charge or released.
If a transaction has been pending for an unusually long period, check your account details or contact the merchant or card issuer.
What Happens When a Pending Transaction Posts?
When a pending transaction posts, it becomes a finalized charge on your credit card account.
For example, suppose you make a $300 purchase and it initially appears as pending.
If the merchant later submits the final transaction for $300, the pending transaction may change to a posted charge.
Your account will then reflect the completed transaction as part of your posted activity.
However, the final amount does not always have to be identical to the original authorization.
This can happen with transactions where the final amount changes after the initial authorization.
Can a Pending Transaction Disappear?
Yes.
A pending transaction can sometimes disappear without becoming a posted charge.
This can happen when the merchant does not complete the transaction or when an authorization expires or is released.
For example, a merchant may authorize a transaction but later cancel the order. The temporary authorization may eventually disappear.
If the transaction disappears, your available credit may increase again.
However, if you still received the product or service, do not automatically assume that the merchant will never charge you. A merchant could submit a transaction later depending on the circumstances.
Pending Transaction vs Authorization Hold
Pending transactions and authorization holds are closely related, but they are not always exactly the same thing.
An authorization hold is a temporary reservation of available credit created when a merchant requests authorization.
Hotels, rental car companies, gas stations, and restaurants can commonly use authorization holds.
CoreFoxes has a detailed guide explaining Credit Card Authorization Holds, including how they can temporarily reduce your available credit and why the final charge may differ from the original authorization.
A pending transaction can therefore reflect a transaction that is still moving through the authorization and settlement process.
Can a Pending Transaction Affect Your Credit Score?
A pending transaction does not normally create a separate credit inquiry or directly damage your credit score.
However, pending activity can affect your available credit temporarily.
Your credit utilization can also be affected by the balances that are ultimately reported to the credit bureaus.
For example, if several purchases post before your issuer reports your account balance, your reported utilization could be higher.
The important point is that a pending transaction is not automatically the same thing as a reported credit card balance.
What If a Pending Transaction Is Incorrect?
If you do not recognize a pending transaction, do not automatically assume it is fraud.
First, check whether the merchant name looks different from the business name you remember.
Some merchants use a parent company or payment processor name on credit card statements.
You should also consider whether a family member or authorized user made the purchase.
If you still do not recognize the transaction, contact your card issuer and ask about the charge.
If the transaction later posts and you believe it is unauthorized, follow your issuer’s process for reporting and disputing the transaction.
Can You Cancel a Pending Credit Card Transaction?
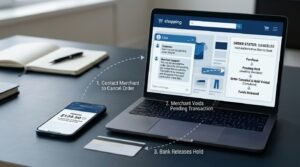
Usually, simply contacting your credit card issuer does not allow you to cancel a legitimate purchase that is still pending.
The merchant may need to cancel the order or transaction.
For example, if you placed an online order and immediately changed your mind, contacting the merchant may be the fastest way to request cancellation.
If the merchant cancels the transaction, the authorization may eventually be released.
However, the exact process depends on the merchant and card issuer.
What If the Pending Amount Is Different From the Final Charge?
The pending amount and final posted amount can sometimes be different.
This is common when the final cost depends on additional charges.
Restaurants are one example because the final amount may include a tip.
Hotels can also place an estimated authorization that is different from the final bill.
Gas stations may use temporary authorization amounts before the final fuel purchase is determined.
When the transaction posts, the final amount should reflect the completed transaction rather than necessarily matching the initial authorization.
How Do Pending Transactions Affect Your Credit Card Balance?
Your credit card account may show several different figures at the same time.
For example:
- Credit limit: $10,000
- Posted balance: $2,000
- Pending transactions: $500
- Available credit: approximately $7,500
The exact numbers can vary depending on your issuer and account activity.
This is why it is important to understand the difference between your posted balance, current balance, pending transactions, and available credit.
You can also learn more about Credit Card Account Review to understand why issuers monitor account activity and how balances, payments, and spending behavior can factor into account management.
What Should You Do When You See a Pending Transaction?
In most cases, there is nothing you need to do.
If you recognize the purchase, you can simply monitor it until it posts or disappears.
However, you should pay closer attention if:
- The amount looks incorrect
- You do not recognize the merchant
- The transaction remains pending for an unusually long period
- Your available credit has fallen unexpectedly
- A transaction appears multiple times
If something does not look right, contact the merchant or credit card issuer.
You should also continue making required credit card payments based on your statement and payment terms rather than waiting for every pending transaction to post.
Why Monitoring Pending Transactions Matters
Checking pending transactions regularly can help you understand why your available credit changes throughout the month.
It can also help you identify duplicate transactions, unfamiliar purchases, and temporary authorization amounts.
For people who frequently travel or use their credit cards for hotels, rental cars, and other services, monitoring pending activity can be especially useful.
It becomes easier to distinguish between money that has actually been charged and credit that has only been temporarily reserved.
Final Thoughts
A pending credit card transaction is generally a transaction that has been authorized but has not yet been finalized as a posted charge.
Pending transactions can temporarily reduce your available credit, but they do not always represent your final account balance.
Some transactions post quickly, while others may remain pending for several days depending on the merchant, issuer, transaction type, and processing conditions.
The best approach is to monitor your account, recognize the purchases you make, and investigate transactions that look unusual or remain pending longer than expected.
Understanding pending transactions can make it much easier to manage your available credit and avoid confusion when your credit card balance changes.

