
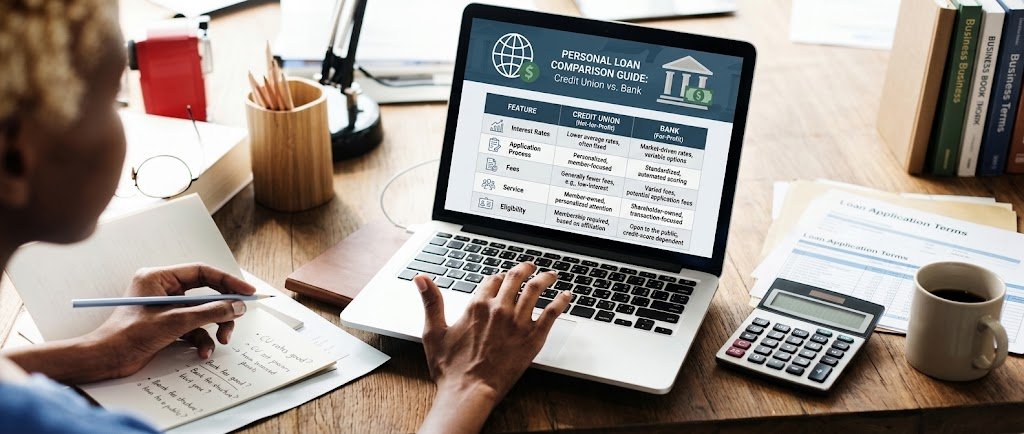
You’ve got a $10,000 home repair staring you down, and two lenders are offering what looks like the same loan. One is the big national bank you’ve used for years; the other is a credit union you’ve been eligible to join all along, thanks to where you work. When it comes to credit union personal loans, that second door is usually where the savings hide.
Most people default to the bank out of habit. But credit unions are not-for-profit, member-owned cooperatives, and that structure tends to show up exactly where borrowers care most: the interest rate, the fees, and the approval process. So where can you actually get the lowest rate in 2026? Let’s break it down.
How Credit Union Personal Loans Work Differently
A credit union is owned by its members, not outside shareholders. Earnings come back to members as lower loan rates, higher savings yields, and reduced fees — that’s the core pitch, and it’s not marketing fluff. According to NCUA data, the national average rate on a 36-month personal loan at credit unions was 10.78% in late 2023, versus 11.37% at banks for the same product. That’s roughly half a percentage point of pure structural advantage.
Federal credit unions also operate under a federal interest rate ceiling — the NCUA Board extended the temporary 18% ceiling through September 2027 — which no bank has.
There’s a trade-off, though. You must be eligible for membership, which usually means sharing a “field of membership”: your employer, your city or county, your school, or a group you belong to. The good news is that many credit unions have broadened eligibility so much that nearly anyone can join through an association or donation of a few dollars. Once you’re in, you can typically keep membership for life.
Deposits at federally insured credit unions are covered up to $250,000 per depositor by the NCUA — the credit-union equivalent of the FDIC insurance that protects bank accounts.
Where Banks Still Win
Fairness matters here. Credit union personal loans aren’t automatically the best deal for everyone.
Banks tend to win on:
- Speed and technology. Large banks often deliver instant decisions and same-day funding through polished apps; some smaller credit unions still run on paperwork and branch visits.
- Availability. Anyone can apply — no membership hoops.
- Product variety. Big banks bundle loans with premium credit cards, private banking, and relationship discounts that credit unions may not match.
- National footprint. If you move states, your bank comes with you; your credit union may not.
The practical move is to treat the bank quote as your baseline and see whether a credit union beats it. Understanding the difference between pre-approval vs. pre-qualification helps you compare offers without dinging your credit.
Credit Union Personal Loans vs Bank Loans: The Rate Math
Here’s a hypothetical, clearly labeled example to show why the rate gap matters.
Say you borrow $10,000 over 36 months:
- At the bank’s average rate of 11.37%, you’d pay roughly $1,850 in total interest.
- At the credit union’s average of 10.78%, you’d pay roughly $1,750.
That’s about $100 saved on a modest loan — and the gap widens with bigger balances or longer terms. On a $25,000 consolidation loan over five years, a one-point difference can save $700 or more.
Keep in mind these are averages, not quotes. Your actual rate depends on your credit profile, income, and debt load. Our guide to personal loan interest rates in 2026 walks through what drives the numbers you’ll actually be offered.
Rates also aren’t the whole cost. Watch for loan origination fees, which can run 1% to 8% and are often deducted from your proceeds before you see a dollar. A credit union with a slightly higher rate but zero origination fee can still be the cheaper loan.
Approval Odds: Who’s More Flexible?
This is where credit union personal loans earn their reputation. Because credit unions serve defined communities and hold loans on their own books, they often weigh factors beyond a raw credit score: your history with the institution, your employment stability, your overall relationship.
If your credit is fair rather than excellent — say, somewhere in the 580 to 670 range — a credit union is frequently more willing to listen than a big bank’s algorithm. Some offer credit-builder or smaller-dollar products specifically designed for members rebuilding their credit. Our article on bad-credit personal loans covers what to expect from any lender in that situation.
Banks, meanwhile, typically reserve their best rates for borrowers with scores well into the 700s, and automated underwriting can be unforgiving. If a bank turns you down, that denial isn’t the end of the road — read our guide on what to do when your loan application is rejected before applying somewhere else.
How to Shop for Credit Union Personal Loans in 2026
The smartest borrowers compare both. Here’s the process:
- Check membership eligibility first — use the NCUA’s credit union locator or ask your employer, and don’t assume you’re excluded.
- Pre-qualify with both a bank and a credit union to see real rates with soft credit checks.
- Compare APR, not monthly payment. APR folds in origination fees and gives you the true cost.
- Ask about relationship discounts. Some credit unions knock off 0.25% to 0.50% for direct deposit or autopay.
- Run the total-cost math on each offer before signing anything.
The NCUA’s rate comparison data lets you benchmark any quote against national averages for banks and credit unions — a useful reality check on whether a “great offer” actually is one.
If the loan is for a true emergency, our piece on emergency personal loans covers when borrowing makes sense and when cheaper alternatives exist.
Common Mistakes Borrowers Make
- Assuming the credit union always wins. Compare real quotes; a bank relationship discount can occasionally flip the result.
- Ignoring fees. A lower rate with a 6% origination fee can cost more than a higher rate with none.
- Applying everywhere at once. Stacking hard inquiries within a short window is fine; dragging applications out over months is not.
- Borrowing more because you qualify. The lender’s maximum is not your budget.
- Overlooking the credit impact. Any installment loan affects your personal loan credit impact — usually neutral-to-positive if you pay on time, but the application itself leaves a mark.
Practical Takeaways
- Credit union personal loans historically carry lower average rates and fees than bank loans, thanks to the not-for-profit structure.
- Banks counter with speed, technology, and convenience — compare both before committing.
- Joining a credit union is often easier than people assume; eligibility has broadened significantly.
- Always compare APR and total repayment cost, not just the monthly payment.
- Pre-qualify with at least one credit union and one bank; the spread between quotes can be hundreds of dollars.
Final Thoughts
The lowest rate usually lives at the credit union — but “usually” is not “always.” Ten minutes of comparison shopping across credit union personal loans and bank offers is one of the highest-paid work in personal finance, and it’s work only you can do.
This article is for educational purposes only and is not personalized financial advice. Rates, fees, and eligibility vary by institution and borrower; confirm all terms directly with the lender.

